Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Personal property, room by room
Condo Contents Calculator
The licensed agent behind this site sets personal property limits from a room-by-room list, not a guess, and this page hands you that list as a free tool. Walk each room, enter what it would cost to replace what you own, and tag each item built in or portable.
You finish with a Coverage C total for your HO-6 and a separate built-in subtotal to check against Coverage A.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
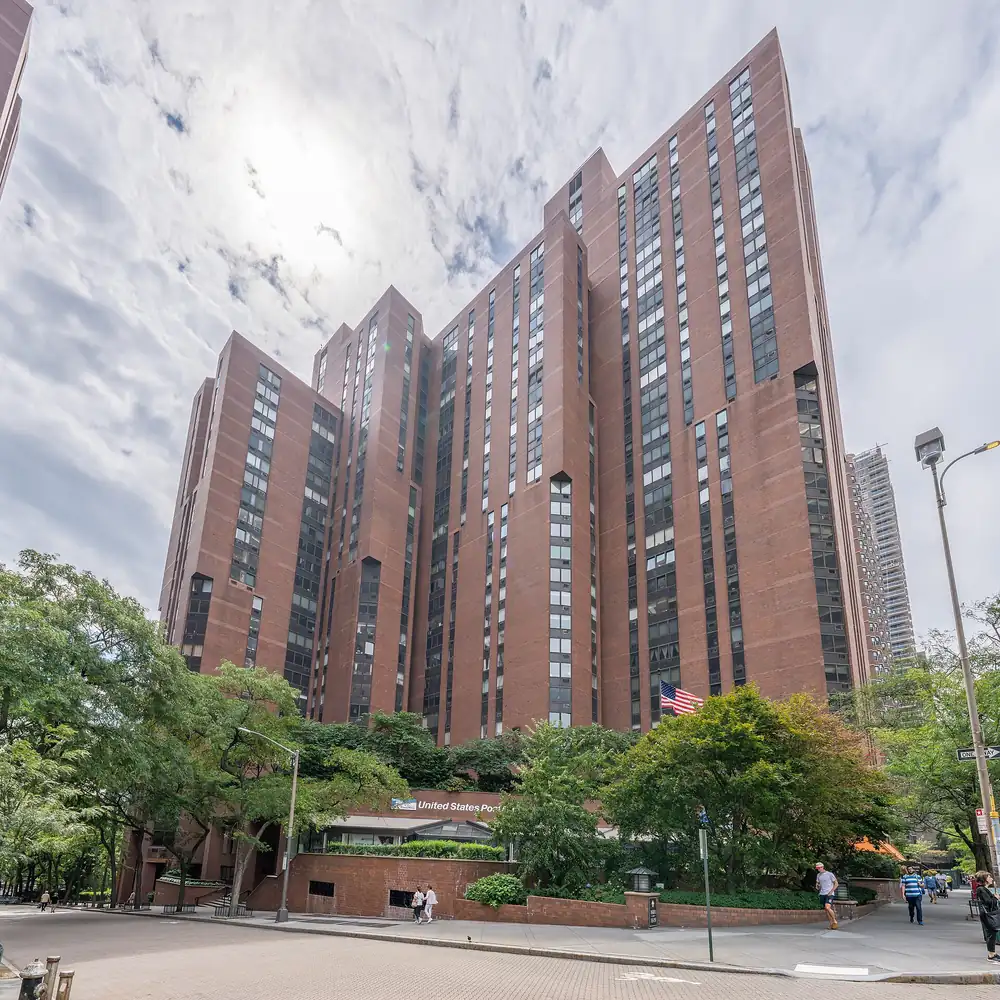
Ruppert Yorkville Towers residential high-rise complex on Third Avenue, Upper East Side, Manhattan. Photo: ajay_suresh, CC BY 4.0, via Wikimedia Commons.
Walk the rooms where the value hides
Lists often come up short: people count furniture and forget drawers, closets and storage. Start here and your total gets honest.
- Open every closet and cabinet
- Flag anything built in
- Include storage outside the unit
Living room contents
Sofa, rugs, lamps, the TV and everything plugged into it.
Kitchen appliances and cookware
Pots, dishes and small appliances add up. A built-in oven or dishwasher usually sits under Coverage A.
Bedroom and closet contents
Clothing, shoes, linens and bags often outrun the furniture itself.
Home office electronics
Computers, monitors, printers and cameras. Write down brands and serial numbers.
Jewelry and valuables
List each piece, then check your policy's special limits for theft.
Storage, garage and balcony contents
A storage locker, bikes, tools and patio furniture are easy to leave off.
Condo Contents Calculator: try it now, room by room
Get the number many owners never write down: what it would cost to replace what you own, split by coverage.
- Choose replacement cost or actual cash value
- Tag each item built in or portable
- Download a CSV for your records
Pick a room, add it, and list what is in it. For each item, enter what a similar one would cost to buy today. Nothing you enter leaves your browser.
Room-by-room contents list: is it A or C?
Add what is in each room and what it would cost to replace. Tag each item built in (usually Coverage A) or portable (Coverage C). Check your policy: forms differ. Nothing leaves your browser.
Read your total as two numbers, not one
The portable total points to your Coverage C limit. The built-in subtotal is your check on Coverage A.
- Portable items: Coverage C
- Attached items: look at Coverage A
- Your policy wording decides
Coverage C pays when things in your unit, furniture, clothing, computers and TVs among them, are damaged, stolen or destroyed by a covered loss1.
Coverage A is for permanently installed property in the unit, where the association's insurance stops short of it2.
A quick test: if you would take it with you when you move, it is usually Coverage C. If it is attached and would stay, look at Coverage A.
Go deeper: appliances, state lists and the master policy line
These descriptions paraphrase a plain-language summary of the condo form in New Jersey's insurance regulations; your own policy's wording controls.
Built-in vs portable appliances in a condo
Appliances are where owners get stuck. The working rule: on the standard HO-6 form many carriers use, built-in appliances usually belong to Coverage A; check your policy3.
A built-in wall oven, cooktop or dishwasher usually belongs with the unit. A freestanding washer, a countertop microwave or a portable air conditioner is usually a belonging. When in doubt, tag it the way your policy reads and ask.
State law can change who insures the item in the first place. In Florida, the association's policy must leave out a list of interior items, including floor, wall and ceiling coverings, electrical fixtures, appliances, water heaters, water filters, built-in cabinets and countertops, and window treatments that serve only the unit4, so those fall to the owner. See the Florida page.
Condo insurance dwelling vs personal property: the master policy draws the line
How much of your list belongs under Coverage A depends on what the master policy covers inside units. An all-in policy often reaches finishes, fixtures and owner improvements; an all-in policy that excludes improvements usually stops at the original finishes; a bare-walls policy leaves nearly the whole interior to you.
Those labels are loose. Your declaration and the master policy summary say what you actually have. Walls-in sizing lives on the coverage sizing page.
Pick the value basis that matches how your policy pays
The same list gives two different totals. Set your limit on the wrong one and a large claim can come up short.
- Replacement cost: generally the price of a new item
- Actual cash value: generally less depreciation
- Your declarations page names the basis
On most forms, replacement cost means what a new item of like kind and quality costs today, so a worn sofa is valued at the price of a comparable new one.
Actual cash value generally means replacement cost minus depreciation for wear and age. How depreciation is figured varies by company and state, so read your form.
Go deeper: how a replacement cost claim usually pays out
Your policy's loss settlement terms decide which one a claim pays. If your contents are covered on a replacement cost basis, set the limit from replacement cost figures.
Many policies that pay replacement cost pay the depreciated amount first and the rest once you replace the item, so keep receipts for what you buy to replace items. Check your declarations page for the loss settlement basis.
Protect jewelry and valuables past the special limits
A ring burned in a covered fire and the same ring stolen can be paid differently. Your form's special limits explain why.
- Theft of jewelry often has a sublimit
- Cash, furs, silverware and firearms often do too
- Scheduling can give an item its own stated value
Many policy forms put special limits on certain categories. Cash, and theft of jewelry, watches, furs, silverware or firearms, are common examples, and on many forms the jewelry limit applies to theft in particular.
If a piece is worth more than its sublimit, ask about scheduling it: listing it on the policy with its own stated value, usually backed by an appraisal or receipt.
Go deeper: why your total and the payout can differ
In a covered fire, the ring may be paid within your overall Coverage C limit; stolen, it may be capped at the theft sublimit. Forms differ, so check yours.
The calculator's total shows what you own. The special limits section shows the most the base policy would pay for it, so read the two side by side.
Turn your inventory into something an adjuster can use
A claim is easier to settle when you can show what you owned, and a few habits now make that simple.
- Photos or video, cabinets open
- Serial numbers and receipts
- A copy stored away from the unit
- Open every closet, cabinet and drawer. Clothing, linens, kitchenware and tools add up faster than furniture.
- Take photos or a slow video of each room, with doors open. Date the files.
- Record brands, models and serial numbers for electronics and appliances.
- Store a copy away from the unit, such as a cloud folder or an email to yourself.
Go deeper: the inventory habits people skip
- Keep receipts or order confirmations for larger purchases, and note where you bought older items.
- Include the spaces outside the unit: a storage locker, a garage space, the balcony furniture.
- Update the list when something changes: a major purchase, a gift, a move of items into storage.
A copy kept off site means a fire or leak does not take the list with it.
Why owners usually need more than contents-only cover
Contents-only cover suits renters. As an owner you usually have walls-in property, liability and extra living costs to protect as well.
- Coverage A for the parts you own
- Loss of use if you have to move out
- Lenders often require the full policy
Many owners have something inside the unit that the master policy does not cover, whether original finishes in a bare-walls building or upgrades made since.
An HO-6 bundles Coverage A for those parts with Coverage C for belongings, plus liability. On the standard form it also carries loss of use, which pays extra living costs above your normal ones if covered damage forces you out of the unit for a while5.
Go deeper: when a lender insists on a unit policy
Fannie Mae's rules, for example, require one if the master policy leaves any part of the unit interior or its improvements uncovered, or has a per-unit deductible6.
Bring your total and see how each company settles it
Two policies with the same contents limit can pay very differently on valuables and settlement terms; a side-by-side view shows you where.
- Personal property limits compared
- Loss settlement terms compared
- Special limits on valuables compared
Bring your calculator total and your Coverage A subtotal. The agent behind this site compares personal property limits, loss settlement terms and special limits for valuables across multiple carriers, and you decide which fits.
Ask each company which discounts apply to your unit; availability varies. Requesting a quote does not bind coverage or change the policy you have now.
Contents and personal property questions
Does personal property insurance on a condo policy cover jewelry?
Yes, but often with a special limit, especially for theft. Check the special limits section of your policy form. For pieces worth more than that limit, ask about scheduling them with their own stated value.
How do I calculate personal property coverage for my condo?
List what is in each room, including closets and storage, and enter what each item would cost to replace today. Add the rooms up. Use replacement cost figures if your policy pays on that basis. The calculator on this page does the adding and exports a CSV you can keep.
Is a built-in dishwasher Coverage A or Coverage C?
Usually Coverage A: on the standard HO-6 form many carriers use, a built-in appliance usually counts as part of the unit under Coverage A3. Forms differ, so check your policy, and ask your insurer if the wording is unclear before you tag it.
Does my condo policy cover belongings when I travel?
Many HO-6 forms extend Coverage C to belongings while you travel, often with conditions, and some set a lower limit for property usually kept at another home you own. Read the Coverage C section of your form, and list anything you often travel with, like a laptop or camera, so you know its value.
Can I buy contents-only insurance for a condo I own?
An owner usually needs an HO-6, not a contents-only policy, because you are often responsible for parts of the unit the master policy leaves out. Your declaration and the master policy summary show what those parts are.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.