Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Condo, co-op and townhouse owners
HO-6 vs HO-3
A licensed insurance agent first works out whether your home calls for a unit-owner form or a whole-house form, then compares that form across several companies. A quote on the wrong form answers the wrong question.
The one-line answer: an HO-3 insures a whole house its owner is responsible for, and an HO-6 insures a unit owner's share of a building an association insures. How you own the property and what your documents say decide, not how it looks.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
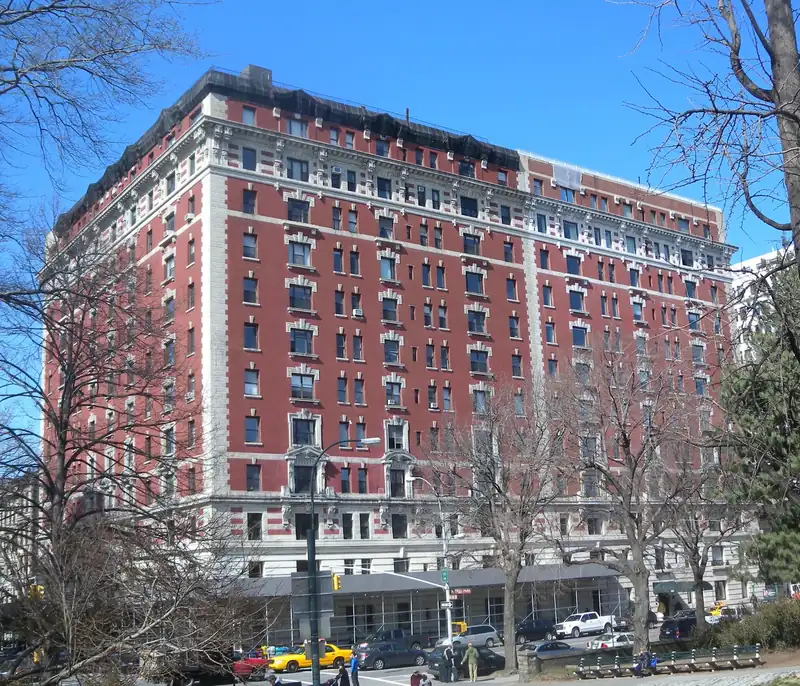
Pre-war apartment buildings at 251 and 257 Central Park West, Upper West Side, Manhattan. Photo: Jim.henderson, CC0, via Wikimedia Commons.
HO-6 vs HO-3: it comes down to who insures the structure
Same family of policy, different job. Find out who insures the roof and walls, and the right form follows.
- HO-3: you insure the whole building
- HO-6: the association usually insures the shell
- Your documents say which one you are
An HO-3 is built for a house
Its dwelling coverage is sized to rebuild the whole structure, roof to foundation, plus a separate line for a detached garage, shed or fence. Nobody else's policy sits underneath it.
An HO-6 is built for a condo unit
It assumes someone else insures the shell. It covers the part of the unit, the belongings and the liability left to you.
A townhouse can go either way
The building style tells you nothing. The legal form of ownership and the association's documents decide.
Go deeper: how a condo act puts the building on the association
Condo acts and declarations commonly put the building on the association. Ohio's condo act, unless the declaration or bylaws say otherwise, has the board carry fire and extended coverage on all buildings and structures for the benefit of every owner1 (see Ohio). The unit-owner policy guide takes each coverage part in turn.
See where the two forms differ, line by line
Same coverage letters on both. Coverage A is a whole house on one and a slice of a unit on the other.
- Dwelling coverage is where they split
- Belongings and liability look alike
- Loss assessment matters far more on a condo
The HO-6 column paraphrases a plain-language summary of the condo form in New Jersey's insurance regulations. It is not every state's rule, and your policy's wording controls.
| Coverage line | On an HO-3 (house) | On an HO-6 (condo unit) |
|---|---|---|
| Dwelling (Coverage A) | The whole house, sized to rebuild it | Only what is permanently installed in the unit and missing from the association's policy2 |
| Other structures | Detached garage, shed, fence on your lot | Shared structures are usually the association's; ask about anything you alone own |
| Personal property (Coverage C) | Your belongings | Items kept in the unit, like furniture, clothing, computers and TVs, when a covered loss damages or destroys them or they are stolen3 |
| Loss of use (Coverage D) | Extra living costs while the house is repaired | Living costs over your usual ones during a temporary move, when covered damage makes the unit uninhabitable4 |
| Liability (Coverage E) | Claims against you for injury or damage to others | A defense in certain lawsuits, and coverage if you are found legally responsible for another person's injury or property damage5 |
| Medical payments (Coverage F) | Guests' medical bills | Medical bills for people hurt on the property6 |
| Loss assessment | Matters only if the home is in an association | Central: your share of an association bill after a covered loss |
Your Coverage A depends on the documents, not the floor plan
Two neighbors in one building can need very different Coverage A limits. The declaration and the master policy explain why.
- Owner upgrades often fall outside the master policy
- Built-in appliances usually sit under Coverage A
- Contents and liability questions stay the same
On an HO-3, Coverage A is the house. On an HO-6, it is only the slice of the unit your documents leave to you, and that slice can be thin or thick.
Built-in appliances usually sit under Coverage A on the standard HO-6 form many carriers use, so check your policy7.
Go deeper: one state's rule, and what stays the same
North Carolina's condo act has the association policy include the units if reasonably available, but it need not include improvements and betterments that owners install8 (that act applies to condominiums created after October 1, 19869; see North Carolina).
Personal property and liability work much the same way
Your belongings, your extra living costs and your liability follow you on either form. The questions carry over too: replacement cost or actual cash value on contents, what liability limit fits what you own, and how the form handles loss of use.
Plan for the master deductible and special assessments
The association's deductible and a special assessment can both reach you. Depending on the form, loss assessment coverage may help with each.
- A master deductible can be passed to owners
- A large shared loss can become an assessment
- How much it helps depends on the form
A condo policy is a homeowners policy on a different form for a different job. It leans on the master policy and fills what that policy leaves out.
If shared property suffers a covered loss bigger than the master policy covers, every owner can be billed a share. See the loss assessment guide for limits and what it will not pay.
Go deeper: how two states handle the master policy deductible
The master policy deductible can land on a unit owner
An Illinois board can cover a master policy deductible as a common expense, assess it after notice and a hearing to the owners who caused the damage or where the loss began, or make the owners of the affected units pay it10 (see Illinois).
In Pennsylvania, whatever part of a loss the deductible leaves uninsured is levied by the executive board11 (for condominiums created after the act's 1980 effective date12; see Pennsylvania). Your unit-owner policy is where you plan for that bill.
Townhome owner? Three questions settle your form
Answer these in order to narrow down whether to quote a unit-owner form or a whole-house form.
- Condo unit, association insures it: usually HO-6
- You own and insure building and lot: often HO-3
- Unclear or mixed: get the documents read
- Does the declaration create condominium units, with the association insuring the structures? Then you usually insure what the documents leave you, on a unit-owner form, even with your own roof and front door.
- Do you own the building and the lot, and do the covenants make you insure the structure? Then you need a policy that rebuilds the whole townhouse, often an HO-3.
- Still unclear, or a mix, such as a condominium whose declaration makes you insure the building? Have a licensed agent read the documents before you choose.
HOA dues alone do not change the answer. They may pay for a clubhouse, not your walls.
Go deeper: documents that settle the townhouse question
Documents that settle the townhouse question
Some setups are mixed. Virginia's condo act does not itself require a master property policy; it lets the condominium instruments require the association to carry one13 (see Virginia). Ohio lets a board approve owner-built patios, decks or fences on limited common elements as long as the unit owner maintains and insures them14. Read these before you choose:
- The declaration or covenants, and the bylaws on insurance
- Your deed, which shows whether you own the land
- The association's master policy summary or certificate
- The resale certificate or disclosure packet, if you are buying
Picking the wrong form can leave the structure, or your share of it, uninsured.
Moving from a house to a condo? Here is what changes
Your old homeowners habits carry over, mostly. Two new line items appear, and your dwelling limit usually shrinks.
- Dwelling coverage narrows to your slice
- Loss assessment and the master deductible appear
- Belongings, liability and loss of use carry over
Get the master policy summary before you set new limits. It shows how much of the unit your Coverage A has to reach.
Many people who move from a house simply carry their old agent's company over. That can work, but it skips the check of whether another company treats a condo unit differently.
Get the right form quoted by several companies
Settle the form first, then compare. The agent reads your documents, picks the form that fits, and lines up several quotes.
- Same limits on every quote
- Ask each company which discounts apply
- The quote itself binds nothing
The agent reads the ownership documents, settles which form fits, and then quotes that form with identical limits across several companies. You decide.
Ask every company which credits your home qualifies for, for example protective devices or combining policies; availability varies by company. Your coverage changes only when you accept a policy and it is issued. Or send a quote request.
HO-3 and HO-6 questions
What is the difference between an HO-6 and an HO-3?
An HO-3 is built for a house its owner insures from the foundation up. An HO-6 is built for a condo owner's share: the part of the unit the association does not insure, plus belongings and liability. The association's master policy usually covers the rest of the building.
Is condo insurance the same as homeowners insurance?
Condo insurance is a type of homeowners insurance, written on the unit-owner form. It usually skips most of the structure because the master policy handles it, and it adds attention to loss assessment and the association's deductible.
Should a townhome have an HO-3 or an HO-6?
If the townhome is a condominium unit and the association insures the structure, usually an HO-6. If you own it fee simple and must insure the building, often an HO-3. The legal form of ownership and the documents settle it, so have a licensed agent read them.
Can I put an HO-3 on my condo?
A condo unit is normally written on a unit-owner form because the association insures the structure. If your documents make you insure an entire building yourself, a carrier may write a different form. That is a question for a licensed agent with your documents in hand.
What changes if I move from a house with an HO-3 to a condo?
Your dwelling coverage shrinks to the part of the unit the documents leave you, and two new items appear: loss assessment and the association's deductible. Belongings, liability and loss of use carry over. Get the master policy summary before you set the new limits.
Which form does a mortgage lender want for a condo?
Fannie Mae's guide asks for a unit owners policy in two cases: part of the unit interior or improvements sits outside the master policy, or the master policy uses a per-unit deductible15. Other loan programs have their own rules, so ask your lender for them in writing.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.