Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
CondominiumInsuranceQuotes.com: Condo Insurance and HO-6 Quotes
Your association's master policy insures the building. Condo insurance, the HO-6 policy, covers what it leaves to you: interior finishes and fixtures, your upgrades, your belongings, your liability and a place to stay after a covered loss.
A licensed insurance agent finds where your declaration draws that line, then compares several companies on the same limits, side by side, in one call. You decide. A quote does not bind anything.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
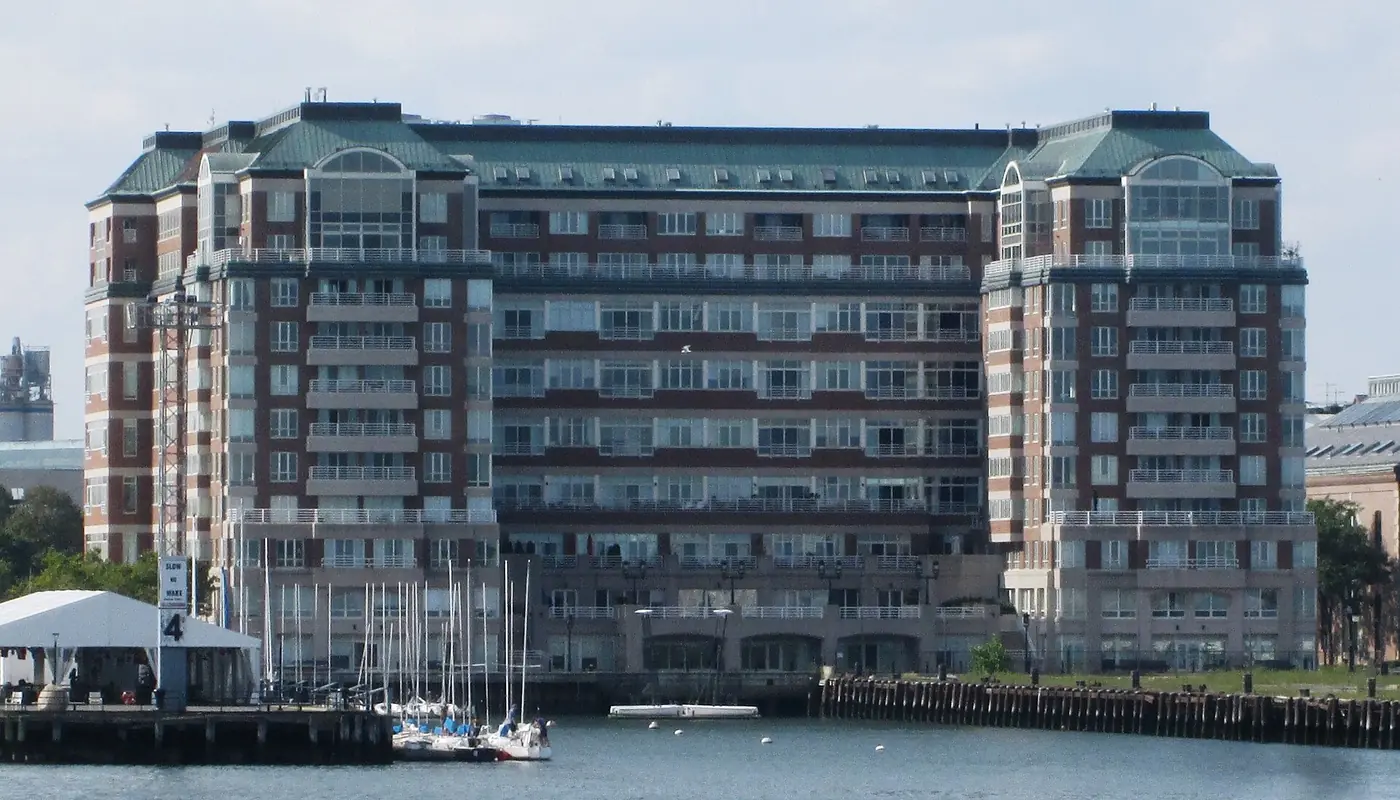
Flagship Wharf, a waterfront residential building in the Charlestown Navy Yard, Boston, seen from Boston Harbor. Photo: Beyond My Ken, CC BY-SA 4.0, via Wikimedia Commons.
Find what your master policy leaves you holding
The association insures the building, not your kitchen, your things or your liability. Know your side of the line now.
- Your declaration and bylaws draw the line
- The line moves from building to building
- Your HO-6 should start exactly where theirs stops
Why it matters to you: learning who insures your floors, cabinets and upgrades is far easier now than in the middle of a claim.
If nobody read the master policy with you, your walls-in coverage may be sized to a guess. Tap your policy type above, then check it against the association's certificate or summary.
Go deeper: interior finishes and owner upgrades, state by state
Interior finishes and fixtures
Flooring, wall and ceiling coverings, cabinets, countertops and light fixtures sit on the line between the master policy and yours. State law or the declaration decides the side.
Florida's condo act has the association's coverage leave out items inside a unit that serve only that unit, among them appliances, water heaters, built-in cabinets, countertops, window treatments, electrical fixtures and the coverings on floors, walls and ceilings1 (see Florida).
Illinois requires the association's property policy to cover the units and, unless the board decides otherwise, their bare walls, floors and ceilings2 (see Illinois).
Owner improvements and betterments
Upgrades you or an earlier owner installed, such as tile, a remodeled kitchen or built-in shelving, often fall outside the master policy even when the original finishes are inside it. Many HO-6 forms insure those upgrades under Coverage A; check your policy.
North Carolina's condo act does not require the association policy to include improvements and betterments that owners installed3 (that act governs condominiums created after October 1, 19864; see North Carolina).
Pennsylvania's required association policy covers the units without the improvements and betterments installed in them5 (for condominiums created after the 1980 act took effect6; see Pennsylvania).
Go deeper: your belongings, liability, loss of use and the master deductible
Personal property in the unit
Furniture, clothing, electronics, kitchenware, bikes and whatever sits in your storage locker belong to you. A master policy is written for the building and the association, not your belongings, so plan on your own Coverage C carrying them.
Ask whether your quote settles at replacement cost or actual cash value. Many replacement cost forms pay the depreciated amount first and the balance once you replace the item.
Personal liability, in the unit and beyond
If a guest slips on your kitchen floor, or a leak from your dishwasher damages the unit below, the claim may point at you rather than the association.
An Illinois board may, through the declaration, bylaws or a rule, require owners to carry personal liability coverage and coverage for damage their unit causes to another unit7 (see Illinois). Your bylaws may set a similar rule.
Your share of the master deductible
When the master policy pays a claim, its deductible still has to come from somewhere, and the governing documents often let the board pass part of it to owners.
In Virginia, the resale certificate must warn a condo buyer that an owner can be held responsible, under the governing documents, for all or part of the deductible8 (see Virginia). Learn the master deductible before you set your loss assessment limit.
Loss of use after a covered claim
A covered loss that makes the unit unlivable leaves you paying for a hotel or a short lease while repairs run. The master policy is written for the building, not your living costs, so this sits on your own policy as loss of use (Coverage D). The limit and how long it lasts vary by form.
Know what each part of your HO-6 pays for
An HO-6 is several coverages in one policy. Knowing each part tells you which limit to raise and which to question.
- A covers your walls-in, C covers your things
- D, E and F: living costs, lawsuits, guest injuries
- Loss assessment pays your share of building losses
The standard form is HO 00 06, and many companies write close versions of it, so the letters usually line up from one company to the next.
The limits, the settlement terms and the exclusions are where policies differ, and that is exactly what a side-by-side comparison puts on one page.
Same letters, different policies. The wording decides what a claim pays.
Go deeper: each coverage letter in plain words, and what to check
To explain the letters, this part paraphrases a plain-language summary of the condo unit-owner form that appears in New Jersey's insurance regulations. That summary is not every state's law, and your own policy's wording controls.
Coverage A: dwelling inside the unit
Coverage A handles property permanently installed in your unit when the association's policy does not already cover it9. Size it to what the declaration leaves you and what rebuilding that would take, not to the price you paid for the unit.
Coverage C: personal property
Coverage C pays for the furniture, clothes, computers, TVs and other things you keep in the unit if a covered loss damages them, destroys them or they are stolen10. Count it room by room, and check the special limits many forms set for theft of jewelry, for cash and for other listed items.
Coverage D: loss of use
Coverage D pays the extra cost of living elsewhere, above your normal expenses, while covered damage keeps you out of an uninhabitable unit11. For a unit you rent out, ask how the form handles lost rent.
Coverage E: personal liability
Coverage E pays for your defense in certain lawsuits and covers you when you are held legally responsible for another person's injury or property damage12.
Coverage F: medical payments
Coverage F pays the medical bills of people injured on your property13. On many forms it is meant for guests, not for you or your household, and it has its own limit on the declarations page.
Go deeper: loss assessment coverage, your share of a building loss
Loss assessment coverage
Loss assessment coverage may help when the association bills owners for a shared loss, say wind damage to several roofs beyond what the master policy limits pay, and an assessment whose cause your own policy covers is covered as well14.
The loss assessment guide goes through limits and exclusions.
Get condo insurance that fits how you use the unit
Live there, rent it out or leave it empty for the season? Each one changes the policy a company will write.
- Tell each company the real use up front
- A policy written for another use may not fit
- Pick your card below
Primary-residence condo
You live there most of the year. The standard owner-occupied HO-6: walls-in, belongings, loss of use, liability and loss assessment.
Long-term rental condo
A tenant lives there. Companies often use a landlord version or an endorsement, sometimes with lost rent. The tenant insures their own things.
Short-term rental condo
Nightly or weekly guests mean more turnover and more liability. Disclose it, and check your association's rules too.
Seasonal or snowbird condo
Empty for months? Expect questions about the water shutoff, the heat or air, and who checks on the unit.
Co-op apartment insurance
You own shares and hold a lease. Whatever the lease and the building policy leave out is yours to insure.
Go deeper: rentals, vacancy wording and co-op leases
Landlord coverage for a rental condo
When a tenant lives in the unit, the policy changes. Many companies write a rented unit on a landlord version of the unit-owner policy or add an endorsement, covering the building items you own inside the unit, your liability as the owner and often lost rent after a covered loss.
Your tenant's belongings are the tenant's to insure, usually with a renters policy (HO-4).
Short-term rental condo endorsements
Renting by the night or the week is a different risk from a lease: more guests, more turnover, more liability exposure. Disclose that use when you ask for a quote. Many forms treat short-term rental differently, some need an endorsement, and your association's rules may limit it on their own.
Snowbird condo vacancy wording
A unit that sits empty for months raises the questions companies ask about vacancy and unoccupancy: is the water shut off, is the heat or air left on, and who checks on the unit. Say how long you are away each year and read the vacancy wording in the form.
Co-op proprietary lease and your coverage
In a co-op you own shares in the corporation that owns the building, and with them a proprietary lease, meaning the long-term lease on the apartment that comes with the shares allocated to it15 (see New York). Read the lease next to the co-op's building policy: whatever the pair leaves out is yours to insure.
Water from upstairs? Know who pays first
One leak from above can pull three policies into one claim. Knowing which answers for what keeps your claim moving.
- Where the water started decides a lot
- Your declaration sets the split
- Report a leak to both association and insurer
A leak from upstairs can damage the building, your finishes and your belongings at once. That puts the master policy, the upstairs owner's policy and yours in the same claim.
Who pays turns on where the water started, what the declaration says and each policy's deductible. The full walk-through: water damage from the unit above.
Go deeper: what to do when water comes through the ceiling
First steps after water damage in a condo
- Stop what you can: shut off your own water supply if the source is in your unit, and move belongings out of the way.
- Photograph everything before cleanup, including the ceiling, the floor and damaged items.
- Tell the association or manager right away, and tell the upstairs owner if you can reach them.
- Call your insurer to report it, and keep receipts for any emergency drying or repairs.
- Keep damaged items until the adjuster has seen them, unless they pose a hazard.
If water from your unit damages the unit below, your personal liability coverage may come into it. Check your policy and your declaration for how the association handles its own deductible on a water loss.
Close the five condo insurance gaps before a claim
Five gaps sit between the master policy and yours. Each one is settled by documents you can read before anything goes wrong.
- Swipe through all five
- Each links to a tool or guide
- Many fixes are a limit or an endorsement
Go deeper: the rules behind each gap
Built-in appliances and Coverage A
Built in or portable decides the letter. Built-in appliances usually count as Coverage A on the standard HO-6 form, the one many carriers use; check your policy.16 Freestanding items you would take with you usually count as personal property.
Master policy deductible rules
Illinois gives the board three choices: absorb it as a common expense, assess it (once owners get notice and a hearing) against those who caused the damage or whose unit the loss started in, or make the owners of the damaged units pay it17 (see Illinois).
In Pennsylvania, the part of a loss left uninsured by the deductible is levied by the executive board under the Act's special expense allocation rules18 (see Pennsylvania). Whether your own policy helps with that bill depends on the form: see the loss assessment guide.
Vacant condo unit questions to ask
A pipe that bursts in an empty unit can run until someone notices. Tell the company how long the unit sits empty, ask what the form expects of you while you are away, and set your limits with how much condo insurance you need.
Special assessment coverage limits
Loss assessment coverage responds to a cause your own policy covers, and only up to its limit. Florida requires unit-owner policies to carry at least $2,000 of loss assessment coverage for all assessments from one direct loss, when the loss is a type the policy covers19 (see Florida).
An assessment for routine repairs or reserves is generally not covered, because it is not a loss. Compare your share with your limit in the loss assessment calculator.
Condo insurance by state: see your state's rules
Condo law is state law. Your state shapes what the association insures and what lands on you.
- The condo act split, in plain words
- Deductible and assessment rules
- The state's residual market for unit owners
- Alabama
- Delaware
- Florida
- Georgia
- Illinois
- Indiana
- Iowa
- Maryland
- Massachusetts
- Michigan
- Minnesota
- New Hampshire
- New Jersey
- New York
- North Carolina
- Ohio
- Pennsylvania
- South Carolina
- Virginia
- Wisconsin
Each linked state page covers the condo act, the master policy split, deductible rules and the residual market for unit owners, with sources.
Quotes are available to condo and co-op unit owners in Alabama, Delaware, Florida, Georgia, Illinois, Indiana, Iowa, Maryland, Massachusetts, Michigan, Minnesota, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, South Carolina, Virginia and Wisconsin.
Go deeper: why the same unit is insured differently across state lines
How the association's master policy duty changes by state
New Jersey makes the association insure the common elements and the structural parts of the property against fire and other casualty, paid for as a common expense20 (see New Jersey).
New York's statute leaves it to the documents: the board of managers must insure the building only when its declaration or bylaws, or a majority of unit owners, require it21 (see New York).
Virginia's statute leaves the master property policy to the condominium instruments, which may require one, rather than requiring it directly22 (see Virginia).
Same kind of unit, three different starting points. That is why your own declaration and bylaws, not a general rule, decide where your HO-6 begins.
Get condo quotes from several companies in one call
An agent for one company can show you one company's policy. Comparing several, on the same limits, shows you what else fits.
- Same limits and deductibles, side by side
- Ask each company which discounts apply
- You decide; a quote never binds you
Why compare at all? An agent appointed with a single company can show you that company's policy. That is simply how the role works, and it is no knock on anyone.
Companies do not all see a condo unit the same way. Several quotes on identical coverage let you check whether a different company handles your unit another way.
Many owners have never had their walls-in amount, loss assessment limit or deductible choice reviewed.
Go deeper: discounts and credits to ask every company about
Condo insurance discount questions to ask each company
Ask each company; availability varies by company and state. These are questions, not discounts you can count on, and each company decides what it offers and who qualifies. A quote shows which, if any, apply to your unit.
- Bundling: does insuring the condo with your auto or umbrella policy change anything?
- Protective devices: do smoke detectors, a monitored alarm or building sprinklers count?
- Water protection: do leak sensors or an automatic shutoff valve count?
- Claims history: does a stretch with no claims count?
- Updates: does newer plumbing, wiring or heating in the unit or building count?
- Billing: does paying in full, autopay or paperless billing count?
Go deeper: how a condo insurance quote works, step by step
How a condo insurance quote works with a licensed agent
- Start with the association's master policy and your declaration.
- Size Coverage A to what the documents leave you, and Coverage C to your belongings.
- Set the deductible, loss assessment and liability limits.
- Compare several companies on those same limits and deductibles, side by side.
- You decide which policy, if any, to buy.
A quote does not bind coverage. Nothing changes until you accept a policy and it is issued.
Grab these documents and skip the back-and-forth
A few papers turn a rough quote into a precise one. You do not need all of them to start.
- Your declarations page is the quickest start
- The master policy summary sets your walls-in
- Missing something? Ask the association for it
Your declarations page shows the limits and deductibles you carry today, so the comparison starts from the same coverage.
The master policy summary and your bylaws show where the association stops. That sets your Coverage A.
Go deeper: the full list, and why each item matters
What to have ready for your condo insurance quote
- Your current declarations page, if you already have a policy
- The association's master policy summary or certificate of insurance
- The insurance section of the declaration or bylaws
- Upgrades to the unit since it was built, yours or a prior owner's
- How the unit is used: your home, a long-term rental, a short-term rental or a seasonal place
- Your lender's insurance requirements, if you have a mortgage
Lender requirements for condo insurance
Fannie Mae's Selling Guide sets the minimum unit owners coverage at the higher of two amounts: the master policy's per-unit deductible, if it has one, or what it takes to restore the interior and improvements the master policy leaves uncovered23. Your lender's letter says which rules apply to your loan.
Run your own numbers before you call
Free tools do the math on your own figures, so you walk into a quote knowing what you need.
- No quote or price, just your math
- Guides explain the terms in plain words
- Use them before or after a call
Loss assessment calculator
Your share of the master deductible against your limit. Open the calculator.
Condo contents calculator
Room by room, Coverage A and C totaled apart. Count your contents.
How much condo insurance you need
Set each limit from your own documents. Work through the limits.
Florida hurricane deductible tool
Statute deductible options against your limits. Open the Florida tool.
HO-6 insurance explained
What a unit-owner policy covers. Read the HO-6 guide.
HO-6 vs HO-3
Which form fits a condo or a townhouse. Compare the forms.
Condo insurance cost factors
What moves a unit-owner premium up or down. See the factors.
Condo water damage from the unit above
Whose policy answers a leak from upstairs. Read the water guide.
Go deeper: which tool to open first
- Buying or insuring a unit for the first time: start with how much condo insurance you need.
- Renewal on the way: run the loss assessment calculator against the association's current deductible.
- Not sure your belongings are covered enough: the contents calculator totals Coverage C room by room.
- Florida unit: the hurricane deductible tool on the Florida page does the multiplication. Your declarations page decides the real figure.
These tools do arithmetic on your own numbers. They do not quote or price anything.
Condo insurance questions unit owners ask
Is condo insurance HO-3 or HO-6?
HO-6. The HO-3 is written for an owner who insures a whole house. A condo owner shares the building with the association, so the HO-6 covers only the part of the unit the documents leave to the owner, plus belongings, liability and loss of use. A fee-simple townhouse can be an HO-3 case; see HO-6 vs HO-3.
What insurance should I get for a condo?
An HO-6 sized to your unit: Coverage A for what the declaration leaves you, Coverage C for your belongings, personal liability, loss of use and loss assessment. Start from the association's master policy summary, then set each limit. If you rent the unit out or leave it empty for a season, tell the company, because it changes the policy.
What kind of insurance do I need if I own a condo?
Two layers work together: the association's master policy on the shared building, and your own unit-owner policy for everything the documents hand to you. Check that the second picks up exactly where the first stops. Flood is a separate policy.
Is condo insurance mandatory?
Usually your lender or your association is the one that requires it. Fannie Mae's Selling Guide sets two triggers for making the borrower carry a unit owners policy: some of the unit interior or its improvements is not on the master policy, or the master policy has a per-unit deductible24. Bylaws can require it too.
Why are condos hard to insure?
Most of the complexity sits with the building, not the unit. The association insures a large shared structure, and its terms reach you through the deductible and any assessment. For the unit itself, the questions are about documents: the master policy type, the deductible, and whether the unit is lived in, rented or empty.
What is the rule of thumb for condo insurance?
Start from the documents, not a number. List what inside the unit is yours, estimate what it would take to rebuild that for Coverage A, count your belongings room by room for Coverage C, then set loss assessment against your share of the master deductible. The limits guide walks through it.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.