Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Special assessments and your HO-6
Loss Assessment Coverage
The licensed agent behind this site sizes loss assessment by starting with a number many owners never look up: their share of the association's master-policy deductible. Loss assessment is the part of an HO-6 that can pay toward that share when the association bills owners for a covered loss.
Run your share in the calculator first. Then see what the coverage pays, what it skips and where state law steps in. A bill for reserves or upkeep is a different matter; see why boards levy special assessments and how they are split.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
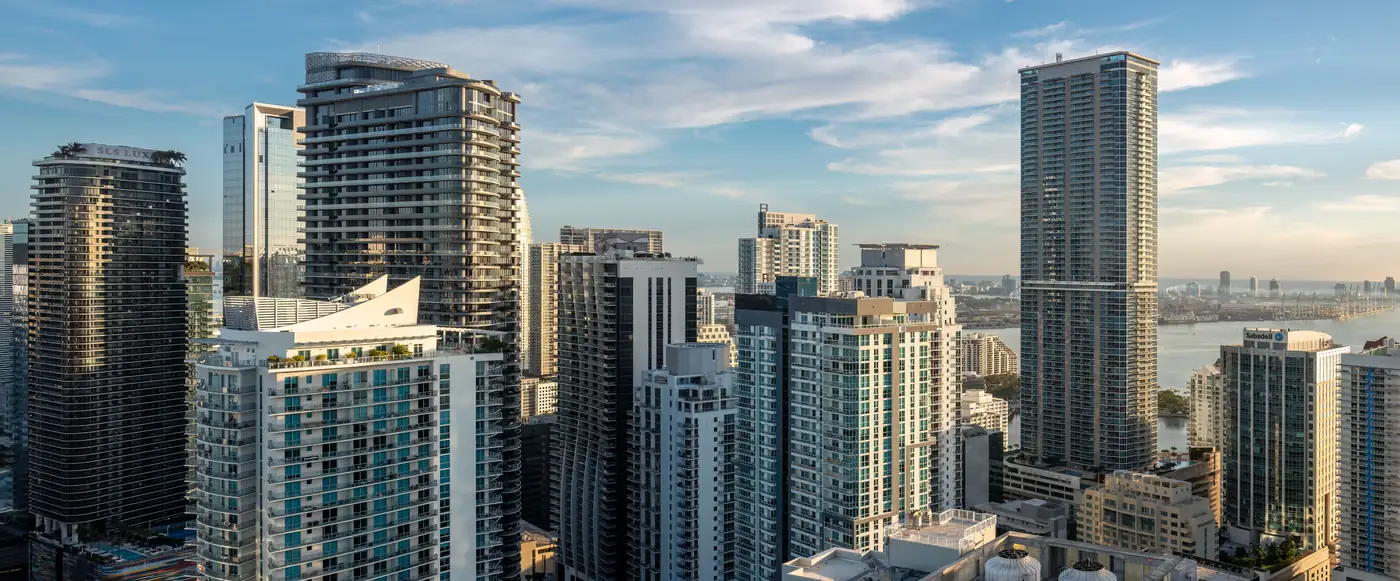
Residential high-rise towers in the Brickell neighborhood of Miami, with Biscayne Bay in the background. Photo: Rhododendrites, CC BY-SA 4.0, via Wikimedia Commons.
Loss Assessment Coverage: run your share now
Put your slice of the master-policy deductible next to the loss assessment limit you carry today.
- Two figures from your documents
- Math only, nothing is priced
- Shows a gap before a loss does
You need: the master-policy deductible (on the association's policy summary or certificate) and your share of the association (a percentage interest in the declaration, or an equal split by unit).
Loss assessment calculator
Math only. Enter the association's master-policy deductible and your share of the association (from the declaration). The result is what your share of that deductible would be, compared with the loss assessment limit you carry.
Whether your loss assessment coverage pays an assessment for the association's deductible depends on your policy form. Ask before you rely on it.
Go deeper: where to find the two numbers
- The master-policy deductible for the loss. It is printed on the master policy summary or certificate. Many master policies carry a separate, larger deductible for certain perils, such as wind, so note each one and run each.
- Your share of the association. Most declarations assign each unit a percentage interest in the common elements, and assessments follow it. Some associations split charges equally by unit.
Treat your result as the floor, then leave headroom
Your deductible share is a starting point, not a ceiling. A bigger loss or a different split can bill you more.
- Run the largest master deductible too
- A per-unit deductible can land entirely on you
- Change limits at renewal, not after damage
A loss past the master policy limits, or a board decision to charge the whole deductible to one unit, can produce a larger bill than the calculator shows.
If your result tops the limit on your declarations page, the difference could fall to you. The calculator does math only; whether a claim pays still turns on the cause and your form.
Many owners carry whatever limit came with the policy and never hold it up against this number.
High-rise owners share the biggest bills; see loss assessments in Miami condo towers.
Go deeper: what can push the bill higher
- A per-unit deductible. Some master policies apply the deductible to each damaged unit instead of the building. That can put the whole amount on you.
- How well the building is insured. Limits close to replacement cost and healthy reserves make a large shortfall less likely. Ask the manager for the master policy summary and the latest reserve figures.
- Timing. A change made after the damage happens usually does not apply to that loss.
Loss assessment is one part of the policy. For walls-in, contents and liability, see sizing the rest of your HO-6, and for the form itself, what each HO-6 coverage part does.
See what this part of your HO-6 can pay
It can pay your share of an association bill for a covered loss to shared property, up to your limit.
- Follows the causes your own policy covers
- Steps in where the master policy falls short
- Often one limit per event
Your association usually insures the building and common areas under its master policy. When a loss costs more than that policy pays, or falls inside its deductible, the association can pass the gap to owners as a special assessment.
Washington's insurance regulator gives a plain example: if wind damages several roofs and the repairs run past the master policy limits, the association can assess the owners, and when the cause is covered under your own policy, the assessment for that cause is covered too1.
Go deeper: how a loss assessment claim runs, step by step
- The building suffers a loss, and the association files on its master policy.
- Whatever that policy does not pay (its deductible, or the amount above its limits) may be assessed to the owners, usually by the formula in the declaration.
- You send the assessment notice to your own insurer, which may pay your share if the cause is covered, up to your limit and after any deductible your form applies.
Many policy forms apply one limit per loss, however many assessments the association sends for that event. Check your policy for how yours handles it.
Check the reason on the bill before you file
A special assessment is any charge on top of your dues, and only some of them are losses your policy can pay.
- Storm or burst-pipe damage: often a covered cause
- Upkeep and reserves: generally not
- Excluded causes stay excluded
Your regular assessment is the dues set by the annual budget. Associations levy special assessments for storms, burst risers, lawsuits, worn-out roofs and short reserves. The reason matters more than the label.
Covered-cause assessment
A fire or a burst pipe in a common area, when your own policy covers that cause. Often payable, up to your limit and subject to your form.
Maintenance assessment
Repainting, repaving or replacing worn-out systems is not a loss, so it is generally not covered.
Reserve or upgrade assessment
Topping up reserves or adding an amenity is a budgeting decision, not a loss.
Excluded-cause assessment
If your HO-6 excludes a cause of loss, an assessment for damage from it is usually excluded too.
Go deeper: assessments charged by a government body
Many forms also exclude an assessment that a government body charges the association. Check your form before you count on it.
Get it in writing: does your form pay a deductible assessment?
Whether loss assessment pays your share of the association's deductible depends on your policy form, and forms differ.
- Some forms pay it
- Some limit it or cap it with a sublimit
- Ask whether the source unit matters
Ask your insurer in writing whether your form covers an assessment for the master-policy deductible, and whether it matters that the damage started in your unit. The deductible itself is printed on the association's master policy.
With quotes from several companies side by side, this wording is one of the easiest differences to spot. With only one form on the table, it is one of the easiest to miss.
Which deductible reaches owners differs by state. See which Ohio deductible lands on owners and how Massachusetts owners choose deductibles line by line.
Supplemental loss assessment coverage: an add-on to the built-in amount
When your share of a bill could top the coverage built into the form, an endorsement can add to it, on its own terms.
- Built-in coverage comes first
- The add-on supplements it
- Its wording sets the terms
The standard unit-owners form already carries loss assessment as an additional coverage, with one limit for a loss however many assessments follow it2. Supplemental loss assessment coverage is an endorsement added on top, for owners whose share could run past that amount.
North Carolina's filed homeowners program for policies starting on or after June 1, 2027 includes a supplemental loss assessment coverage endorsement3. Your own policy and its endorsements decide what is covered, so ask each company for the exact form it attaches and how it counts the added amount.
Maryland will ask for more of it: from October 1, 2027, a unit owner in a condominium made up entirely of residential units must keep a policy with loss assessment coverage of at least $25,0004 (Md. Code, Real Prop. § 11-114.3(b) (Ch. 717 of 2026)4).
Go deeper: earthquake, a sale before the bill, and Maryland's deductible share
Earthquake and loss assessment
The coverage built into the standard form leaves out assessments caused by earthquake or volcanic land shock2. North Carolina's filed program also lists a separate loss assessment endorsement for earthquake5. Ask whether a supplemental amount reaches an earthquake assessment or needs a form of its own.
Which policy pays a loss assessment after a sale
Minnesota sets the order: the policy in force at the time of the loss pays, within its limits and terms, when the same owner still holds the unit as the bill is charged and that policy carries loss assessment coverage6 (Minn. Stat. § 65A.3025, subd. 2(a)6).
If the unit has changed hands before the association charges the assessment, the policy in force on that date pays instead, and the insurer may ask for proof the sale came first7. The same statute treats the assessment and the event behind it as a single loss for underwriting and rating6.
Maryland's deductible share and your loss assessment limit
From October 1, 2027, Maryland makes the owner of the unit where damage starts responsible for the least of the repair cost, the association's deductible or $25,000, instead of a cap of $10,000, and lets the association assess that owner for it8 (Md. Code, Real Prop. § 11-114(g)(2) (Ch. 717 of 2026)8).
Renting the unit out? The association's bill still comes to you as the owner; see unit owners rental to others.
Learn the state rules that shape your deductible bill
Your state can set a minimum limit or steer the deductible toward certain owners, so know the rule where you live.
- Florida sets a minimum limit
- Illinois and Pennsylvania boards route the deductible
- Virginia warns buyers in the resale papers
Florida loss assessment minimum
A unit-owner policy there must include a loss assessment limit of at least $2,000 for all assessments from the same direct loss, when the loss is of a type the policy covers9. Florida unit-owner rules.
Illinois deductible choices
The board may pay it as a common expense, assess it after notice and a hearing to the owners who caused the damage or from whose units the loss started, or charge the owners of the affected units10. Illinois deductible routes.
Pennsylvania deductible gap
The executive board levies the uninsured deductible part of a loss, and any self-insured loss, as a special allocation of expenses11, in condos created after the act took effect in 198012. Pennsylvania's levy.
Virginia deductible notice
The resale certificate has to state that the governing documents may leave an owner responsible for all or part of the deductible on a claim13. Virginia disclosures.
Go deeper: what lenders require about the master deductible
On some forms loss assessment comes built in; on others it is an add-on you ask for. Check your declarations page for a separate loss assessment line and limit.
Lenders care about the deductible too. Fannie Mae's Selling Guide requires a unit owners policy when the master policy has a per-unit deductible14, and sets the minimum unit coverage at no less than that per-unit deductible, if the master policy has one15.
Compare limits and deductible wording on one page
If your current policy came from a single company, you have only seen how that company writes loss assessment.
- Limits lined up side by side
- How each form treats a deductible assessment
- You choose what to buy
The agent behind this site lines up loss assessment limits across multiple carriers, along with how each form handles an assessment for the master deductible. Ask each company which credits apply to your unit; availability varies, and the quote shows any that do.
Have your declarations page and the master policy summary handy. A quote does not put coverage in force; that happens only when you accept a policy and it is issued.
Loss assessment questions
How does loss assessment coverage work?
The building has a loss, the association claims on its master policy, and whatever that policy does not pay can be billed to owners as an assessment. You send the notice to your own insurer, which may pay your share up to your loss assessment limit when the cause is one your policy covers. More on how special assessments are noticed and divided.
Does loss assessment pay my share of the association's deductible?
Sometimes. It depends on the wording of your policy form. Some forms pay an assessment for the master-policy deductible when the loss is a type your policy covers; others limit or exclude it. Get the answer in writing before you rely on it.
Is a special assessment for maintenance covered?
Generally not. The coverage pays for losses from covered causes, like a fire or a burst pipe in a common area. Upkeep, reserve top-ups and upgrades are not losses, so there is nothing for the policy to pay.
How should a Chicago high-rise owner decide how much loss assessment to carry?
Start with the building's master-policy deductible, including any separate deductible for a specific peril, and multiply it by your percentage interest from the declaration. Then allow for the Illinois rule that lets the board assess the deductible to the owners from whose units a loss originated, after notice and a hearing10. A leak that starts in your unit could land the whole deductible on you. See the Illinois deductible statute and condo insurance in Chicago.
Is loss assessment required on a Florida condo policy?
Yes. Florida requires at least $2,000 in loss assessment limits on unit-owner policies, for a loss of a type the policy covers9. You can buy a higher limit; your share of the master deductible is a sensible place to start. See Florida's loss assessment rule in full.
What is supplemental loss assessment coverage?
It is an endorsement that adds to the loss assessment coverage built into a standard HO-6. The built-in part pays your share of an association bill after a covered loss to shared property, up to a set amount. The supplemental form's own wording decides how much more it adds and which assessments it reaches, so read it before you buy.
Does Maryland require loss assessment coverage on a condo policy?
Starting October 1, 2027, yes: the policy a unit owner must keep in an all-residential condominium has to include loss assessment coverage of at least $25,0004. Detached units in a condominium made up entirely of similar detached units are outside that rule. Until it takes effect, check your bylaws.
If the association bills me more than once for the same loss, do I get a new limit each time?
Often not. A common approach is a single limit for the event, however many bills follow it. Set the limit to cover the full share you could owe for one event, and read your policy's wording on repeat assessments.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.