Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Massachusetts condo unit owners
Condo Insurance Massachusetts
A licensed insurance agent behind this site compares Massachusetts HO-6 coverage across several companies, and the short answer is this: the law gives your association the power to insure the common areas1, so your master deed, trust and by-laws decide where its policy ends and yours begins.
Read that line once, and every section below gets easier.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
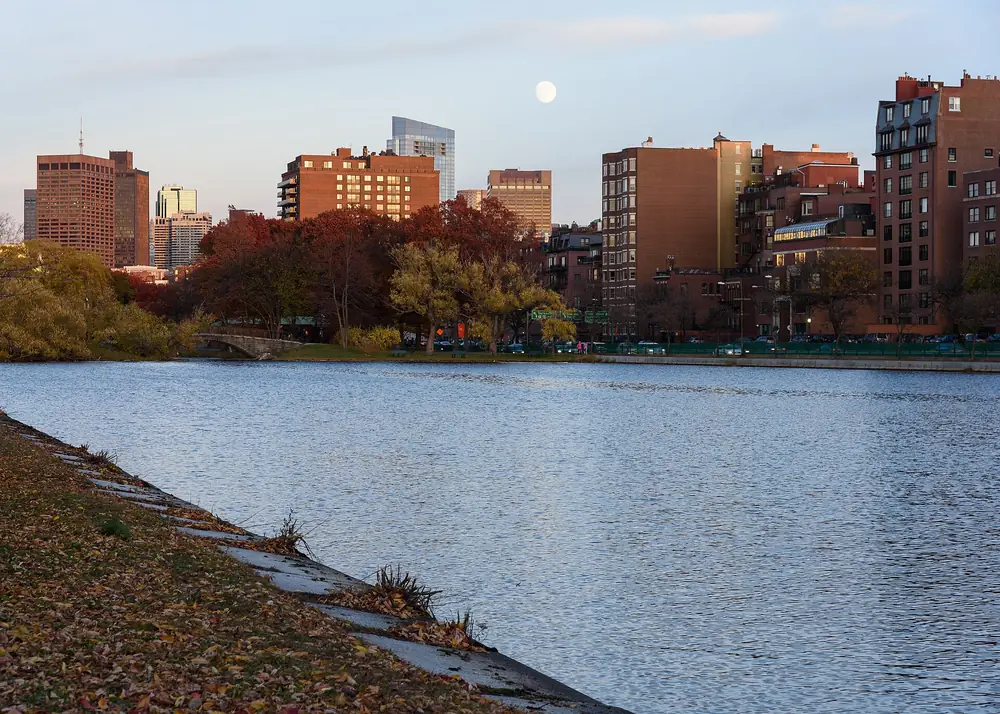
Back Bay residential buildings reflected in Storrow Lagoon, Charles River Esplanade, Boston. Photo: King of Hearts, CC BY-SA 4.0, via Wikimedia Commons.
Condo Insurance Massachusetts: the master deed draws your line
Your own papers, not the statute, tell you how much of the unit your HO-6 has to rebuild.
- The association may insure common areas
- That is a power, not a duty
- Your right to insure your unit stays yours
The organization that runs the building can buy coverage on the common areas and facilities, in its own name, without limiting your right to insure your own unit1 (M.G.L. c. 183A, § 10(b)(3)1).
Three papers settle the split:
- The master deed, which maps the unit and the common areas.
- The by-laws or condominium trust, home of the insurance and repair clauses.
- The master policy or its certificate, which shows what was bought.
Go deeper: bare walls, original fixtures and what each means for you
The statute lets the unit owners' organization, whether a corporation, trust or association, insure the common areas and facilities. The policy is written in the organization's name, and it leaves each owner free to insure his or her own unit for his or her own benefit1.
Notice what it does not say. It is framed as a power, not a duty, and it speaks only of the common areas and facilities.
If the master policy stops at the bare walls, your HO-6 has to rebuild everything inside them. If it covers original fixtures, yours mainly picks up upgrades, belongings and liability. Read both documents to know which you have.
Choose your deductibles on purpose, line by line
Your HO-6 deductibles come from the policy you pick, so each one is a decision, not a default.
- The all-perils line is only the first one
- Wind or named-storm lines may differ
- The master deductible lives in your by-laws
Look past the headline deductible. A policy may carry a separate wind or named-storm deductible, and each one has its own trigger.
Ask how every deductible on the declarations page is triggered before you accept a quote.
Go deeper: the mortgage ceiling on a unit owner deductible
If your mortgage is sold to Fannie Mae, your unit policy's deductible for the required perils cannot exceed the greater of 5% of its coverage amount or $2,5002. The master policy has a deductible of its own, covered in the gaps below.
Check the reserve balance before you buy or renew
Massachusetts makes every condominium keep a replacement reserve. How full it is can shape your next assessment.
- Required for every condominium
- Held apart from operating money
- Ask for the balance and any study
Each condominium has to keep an adequate replacement reserve, funded through common expense charges and held apart from day-to-day operating money3 (M.G.L. c. 183A, § 10(i)3).
The law asks for adequate. Only the board's numbers tell you whether yours is.
Go deeper: what a thin reserve means for your HO-6
Ask the board for the current reserve balance and whether a reserve study has been done. A thin reserve makes a special assessment more likely after a repair the master policy does not pay, and loss assessment coverage is generally not built for wear and tear.
Declined elsewhere? MPIUA still writes a condo form
If you live in the unit, one company's no may not end your HO-6 options.
- MPIUA is the Massachusetts FAIR Plan
- It lists a unit owners form
- Owner-occupied units; ask about the rest
MPIUA, the state's FAIR Plan, lists the Condo Unit Owners Form HO 00 06 in its homeowners program, for an owner-occupied condo unit4.
Ask the plan about its other eligibility rules, then weigh its form and deductibles against any other offer.
Go deeper: a rented, seasonal or empty unit
The plan's listing describes an owner-occupied unit. If you rent the unit out or it sits empty, that listing does not describe your situation, so ask before you count on it and keep the standard market in play.
Insurer stuck? The Division of Insurance takes your call
When a claim, a nonrenewal or a policy term goes wrong and stays wrong, the state is your next call.
- Consumer services line, weekdays
- Call after your insurer says no
- Bring your letters and numbers
Massachusetts Division of Insurance, consumer services: 617-521-7794, a weekday line5.
Have the policy number, claim number and every letter from the insurer in front of you.
Strong wind can reach you through two policies
Wind can damage your interior directly and your budget indirectly, through the master deductible.
- Interior damage: often your HO-6
- Roof and walls: usually the association's policy
- Its deductible may be passed to owners
When the building is opened up, your finishes and belongings are usually on your side. Roof and wall damage usually goes to the master policy when the association insures them, and its deductible may come back to owners if your documents say so.
Check both policies for a separate wind or named-storm deductible.
Five gaps worth closing before your Massachusetts renewal
Swipe through five places a Massachusetts claim can come up short, then tap the letters.
- Winter water and empty units
- Which letter of your HO-6 pays
- Deductibles, assessments and the lien
Go deeper: the Massachusetts rules behind each gap
Water. Where the association's side ends is set by the master deed and by-laws. Whether your HO-6 pays depends on the cause and the form wording, so check your policy. Our guide to water damage from the unit above sets out who to call first.
Coverage letters. Coverage A takes the property permanently installed in the unit that the association's policy does not already insure8. Coverage C is for the furniture, clothing, computers, TVs and other things you own, when theft or a covered loss damages or destroys them9. On the standard HO-6 form, which many carriers use, a built-in appliance is usually a Coverage A item13; check your policy. The condo contents calculator sorts A items from C items, and how much condo insurance you need covers limits.
Master deductible. When a loan sold to Fannie Mae meets a master policy with a per-unit deductible, your unit owners coverage has to be at least that deductible14. Ask whether your loss assessment coverage applies to a deductible assessment; see loss assessment coverage.
Empty or seasonal units. Tell the agent how the unit is used. The FAIR Plan listing is for an owner-occupied unit, so a seasonal or rented unit needs a different answer.
How the Massachusetts assessment lien works
Up to six months of regular, budget-based common expense assessments rank ahead of a first mortgage recorded before you fell behind7 (M.G.L. c. 183A, § 6(c)7). Collection costs and reasonable attorneys' fees join that priority only if the association sent the lender the required notices, and special assessments are not part of it7, though you still owe them.
Loss assessment coverage may help pay a special assessment the association charges for a loss the community suffers, and when the cause is one your own policy covers, the assessment for that cause is covered too15. An assessment for maintenance or an underfunded reserve is a different matter.
Ask more than one company about your unit
One company's quote shows one company's view of your unit. Several, side by side, show how others see it.
- Identical limits make the comparison fair
- Discounts vary by company and state
- Nothing is bound until you accept
An agent who represents a single company can only offer that company's policy. Comparing several on the same master deed, limits and deductibles shows whether another one treats your unit differently.
Many owners bought an HO-6 at closing and never had the walls-in amount, loss assessment limit or deductible looked at again. This is the moment.
Discounts and credits are a question for each company; availability varies by company and state. The written quote shows whether any apply.
Go deeper: what happens after you ask
A licensed agent compares HO-6 options against what your master policy leaves open. You see the forms, limits and deductibles next to each other, and the choice is yours.
A quote does not bind coverage. You are covered only after you accept a policy and it is issued. Massachusetts unit owners can request HO-6 quotes through this site; the agent disclosure covers licensing.
Five items and your Massachusetts quote is ready to build
These papers turn a rough estimate into a quote that fits your master deed.
- The manager can usually supply most
- How you use the unit matters
- Start even if something is missing
When you have them, send a quote request. For background, see how HO-6 insurance works and what affects condo insurance cost.
Massachusetts condo owner questions
Is condo insurance mandatory in Massachusetts?
The statute treats insuring your own unit as your right, next to the association's power to insure the common areas1. In practice, a lender is the usual source of a requirement: under Fannie Mae's guide, a unit owners policy is needed whenever the master policy leaves interior or improvements uncovered, or has a per-unit deductible16. Your by-laws may require one too.
What does a master condo policy cover in Massachusetts?
Whatever the association buys under its power to insure the common areas, so there is no single statewide answer. Ask the board or manager for the policy or certificate and read it next to your master deed and by-laws. Anything it does not cover inside your unit belongs on your HO-6.
Does the Massachusetts FAIR Plan sell condo unit-owner policies?
Yes, for owner-occupied units: MPIUA lists its unit owners form (HO-6) in its homeowners program4. If the unit is rented out or sits vacant, ask the plan before relying on it, and keep comparing standard companies in the meantime.
Can unpaid condo assessments come ahead of my mortgage in Massachusetts?
Part of them can. Up to six months of regular budget assessments outrank a first mortgage recorded before the delinquency, and collection costs join that amount only when the lender received the required notices. Special assessments, fines and interest do not get that priority7.
Who do I call about a condo insurance problem in Massachusetts?
Start with your insurer or the agent who placed the policy, and put the problem in writing. If that does not resolve it, the Division of Insurance takes consumer calls on weekdays at the number in the section above.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.