Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Condo and co-op unit owners
How Much Does HO-6 Condo Insurance Cost?
The licensed agent behind this site can sum up what moves a condo premium in one line: a few choices on your HO-6 declarations page, plus building facts you cannot change. Start with what owners in your state pay on average, from the state insurance regulators' own data.
An average is a starting point, not your price; only quotes compared side by side for your own unit show that. The state averages come first, then the levers, one tap each.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
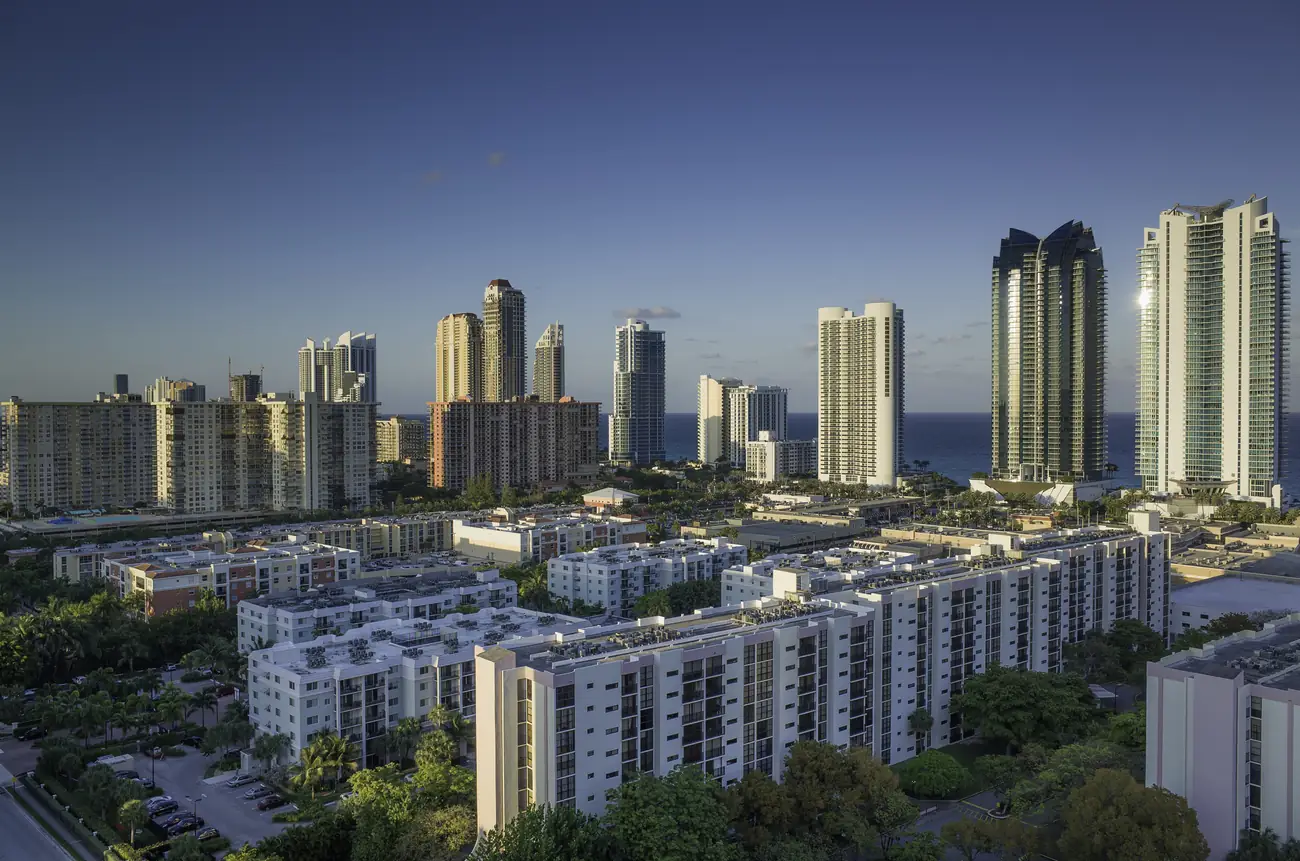
Oceanfront condominium towers and mid-rise residential buildings in Sunny Isles Beach, Miami-Dade County. Photo: Jimmy Baikovicius, CC BY-SA 2.0, via Wikimedia Commons.
Average HO-6 cost by state, from the regulators' own numbers
The national association of state insurance regulators (NAIC) reports what condo and co-op unit owners pay on average in every state.
- One yearly average per state, all limits blended
- Florida sits at the top, Wisconsin at the bottom
- Your own quote can land far from it
NAIC divides the premium written on each policy form by the number of insured units for the year4, so each figure is what an average HO-6 cost for a year of coverage. NAIC itself calls an average an imperfect measure of price, because hazards, economic conditions and real estate values differ from state to state5.
Paying well above your state's line at renewal? That is the moment to have a licensed agent price your same limits with several companies.
See every state's average HO-6 premium
| State | Average yearly HO-6 premium |
|---|---|
| Alabama | $751 |
| Alaska | $521 |
| Arizona | $603 |
| Arkansas | $697 |
| California | $722 |
| Colorado | $657 |
| Connecticut | $459 |
| Delaware | $544 |
| District of Columbia | $504 |
| Florida | $1,146 |
| Georgia | $748 |
| Hawaii | $465 |
| Idaho | $570 |
| Illinois | $522 |
| Indiana | $431 |
| Iowa | $367 |
| Kansas | $433 |
| Kentucky | $481 |
| Louisiana | $992 |
| Maine | $437 |
| Maryland | $468 |
| Massachusetts | $537 |
| Michigan | $413 |
| Minnesota | $468 |
| Mississippi | $764 |
| Missouri | $474 |
| Montana | $642 |
| Nebraska | $442 |
| Nevada | $531 |
| New Hampshire | $421 |
| New Jersey | $521 |
| New Mexico | $521 |
| New York | $781 |
| North Carolina | $637 |
| North Dakota | $338 |
| Ohio | $386 |
| Oklahoma | $752 |
| Oregon | $483 |
| Pennsylvania | $474 |
| Rhode Island | $607 |
| South Carolina | $628 |
| South Dakota | $380 |
| Tennessee | $592 |
| Texas | $999 |
| Utah | $379 |
| Vermont | $413 |
| Virginia | $539 |
| Washington | $512 |
| West Virginia | $375 |
| Wisconsin | $331 |
| Wyoming | $596 |
Texas figures come from the Texas Department of Insurance, whose home policy forms are similar to, but not the same as, the forms used elsewhere7.
Shopping in Florida? InsuranceCompaniesFlorida.com tracks Florida home and condo averages from more recent state reports, so its figure will not match this one. It is a reference site run by the same licensed agent.
Condo Insurance Cost Factors: the settings behind every quote
A handful of settings on your policy shape every quote, and plenty of owners have never had them reviewed.
- Most also change what a claim pays
- Most can be revisited at renewal
- A quote shows how each company prices them
Coverage A walls-in amount
The limit for the floors, cabinets and fixtures the master policy leaves to you.
Personal property limit and basis
What your belongings are insured for, and whether a claim pays new or depreciated value.
Your deductibles
What you pay first on a claim, including any separate wind or hurricane deductible.
Loss assessment limit
How much of an association bill for a covered loss your policy can absorb.
Master policy type
You do not pick it, yet it decides how much of the unit is yours to insure.
Rental or seasonal use
Living there, renting it out and leaving it empty for months are different risks. See how a rented or empty unit changes the policy.
Stop measuring your unit against a neighbor's number
A figure somebody else pays says almost nothing about your own policy, so do not let it anchor your budget.
- Averages blend bare walls with all-in buildings
- Two units in one tower can differ
- A quote on your own limits is the real figure
Published averages mix owners who insure bare walls with owners whose association covers nearly everything, homes with rentals, and flat deductibles with percentage wind deductibles.
Picture two neighbors in one building. One bought the unit as built. The other inherited a previous owner's new kitchen, which the master policy may not cover. Their Coverage A limits will not match, so their quotes likely will not either.
Go deeper: co-op apartments, and why a house quote is no yardstick
Co-op apartments follow the same logic
A co-op owner holds shares and a lease rather than a deed to a unit. The pricing question is the same, though: how much of the apartment the co-op corporation's building policy leaves to you, plus your belongings and your liability.
Ask the co-op's managing agent for the building policy summary before you shop. See co-op insurance in New York.
Condo policy vs house policy: why the premiums do not line up
A house policy has to rebuild the whole structure; a condo policy covers only your share. Set side by side, the two prices say little. Compare what the HO-6 and HO-3 each insure, or read a condo policy next to a house policy in plain words.
Set your walls-in amount from the paperwork, not memory
Coverage A rebuilds your share of the unit's interior. Set it too low and part of a rebuild falls to you.
- Start where the master policy stops
- Count upgrades, yours and a past owner's
- Your lender may set a minimum
This limit is for the part of the unit the master policy leaves to you: flooring, cabinets, fixtures and upgrades. Many owners carry whatever figure came with their first policy and never look at it again.
Work out your own number with the Coverage A estimator.
Go deeper: the lender floor on Coverage A
A mortgage can set a minimum. Fannie Mae's guide wants at least the larger of two amounts: the cost of restoring the interior and improvements the master policy leaves uncovered, or the master policy's per-unit deductible if there is one8 (Fannie Mae Selling Guide B7-3-048).
Treat that as a floor. You can carry more, and rebuild cost is the real target.
Match your contents and liability limits to your real life
Two limits people rarely revisit: what your belongings are insured for, and how far your protection reaches if you are sued.
- Replacement cost: usually the price of a new item
- Actual cash value: usually minus wear
- Liability should fit what you could lose
The contents limit should match what it would take to replace what you own. Replacement cost generally settles at the price of a new item; actual cash value takes off for wear, so it pays less on older things.
Settlement terms vary by form, and the basis you pick is part of the quote.
Build the list room by room with the condo contents calculator.
Go deeper: when replacement cost pays, and umbrella policies
Many forms pay the depreciated amount first and the rest after you replace the item, so hang on to receipts.
Liability limit and an umbrella on top
Personal liability is priced by the limit you choose. Match it to what you own and could lose in a lawsuit.
Ask whether an umbrella policy fits on top. Umbrella carriers usually set a minimum liability limit for the policy underneath.
Turn every deductible into a dollar figure
Your deductible is what you pay first on a claim, and a percentage wind deductible can be the largest one you carry.
- A higher deductible keeps more of a loss with you
- Wind deductibles are often a percentage
- Ask for dollars, not just the percent
The all-other-perils deductible is the part of a covered loss you pay before the policy does. Companies price a higher one differently, and the quote shows how.
In storm-prone states, a separate wind or hurricane deductible is often a percentage rather than a flat amount. Ask each company to show it to you in dollars.
See it worked through for one coastal city in Tampa condo insurance and hurricane deductible math.
Go deeper: lender caps and state wind deductible rules
A mortgage can cap your choice: under Fannie Mae's guide, a unit owners policy deductible can be no more than the greater of 5% of the coverage amount or $2,500, for all required perils9.
Wind and hurricane deductible rules in three states
- Florida: the statute has insurers offer personal lines residential policyholders hurricane deductibles of $500, 2 percent, 5 percent and 10 percent of policy dwelling limits, subject to exceptions10, and it does not define that base for condo unit-owner policies11. See those Florida options turned into dollars.
- New Jersey: insurers may file mandatory hurricane deductibles of up to 5 percent and optional ones up to 10 percent, in the ZIP codes its rule lists and elsewhere only with the department's approval12. See New Jersey's hurricane deductible limits.
- Virginia: for owner-occupied homes and condo units, any property deductible is capped at 10% of the policy's own dwelling limit, which on a condo policy is the unit's limit, not the building value13. See Virginia's cap on a condo unit's deductible.
Size loss assessment to the master deductible you could inherit
When the association bills owners for a covered loss, this limit caps what your policy can pay toward your share.
- Find the master policy deductible
- Find your share in the declaration
- Raise the limit ahead of a loss
Loss assessment can pay toward your share when the association bills owners after a covered loss to shared property.
Florida sets the least a unit-owner policy may carry at $2,000 for all assessments from one direct loss of a covered type14; a large building loss can produce a far bigger bill.
Run your share of the master deductible through the calculator.
Go deeper: when the master deductible comes back to owners
When the master policy carries a large deductible, part of it may come back to owners.
A Virginia resale certificate must describe the association's insurance and say that the governing documents may make an owner responsible for all or part of the deductible15.
An Illinois board has three routes: treat the deductible as a common expense, charge it (after notice and a hearing) to the owners who caused the damage or whose unit it came from, or have the affected owners pay it16.
That exposure shapes how much Coverage A and loss assessment you carry.
Read the master policy before you pick a single limit
The association's policy sets your starting line: the more it covers inside your unit, the less Coverage A you need to buy.
- Bare walls leaves the finishes to you
- All-in covers finishes, sometimes upgrades
- The labels are loose, so read the summary
A policy described as bare walls leaves the interior finishes to owners. One described as all-in covers finishes and fixtures, sometimes including owner improvements.
Many owners were never asked for this summary when their policy was written. How the HO-6 picks up where the master policy stops is explained in the HO-6 guide.
Go deeper: when a lender makes a unit policy mandatory
Lender minimums and the master policy
A unit owners policy becomes mandatory under Fannie Mae's guide once any interior part or improvement is left off the master policy, or once that policy has a per-unit deductible17.
Your lender's letter sets the floor; you can buy above it.
Tell the insurer how you really use the unit
Describe how the unit is used, plainly. A policy that does not match its use can cause problems at claim time.
- Say plainly who lives there
- Rentals may need another form or endorsement
- Ask which building credits apply
A unit you live in, one rented to a long-term tenant, one on a short-term rental platform and a seasonal unit that sits empty for months are rated differently. Some companies write a rented unit on a different form or with an endorsement.
Construction type, the age of the building and its systems, and protective features can all enter the rating. Ask each company whether a mitigation or building-feature credit applies; availability varies by company and state, and the quote shows any that do.
Go deeper: how past claims follow you
Claims history and the premium
Insurers generally look at past claims on the unit and on you as an owner.
Small claims you could have paid yourself can follow you, which is one more reason to set a deductible you can actually pay.
See several companies price the same limits, side by side
One company's quote shows one company's view. Several on identical limits show whether another treats your unit differently.
- Same limits and deductibles, compared
- Ask which discounts or credits apply
- You decide; nothing changes until you do
The agent behind this site sets your limits and deductibles from your documents, then quotes the same package with multiple carriers so you compare like for like. Ask each company which discounts or credits apply; availability varies. You decide.
A quote is not coverage: nothing is bound until you accept a policy and the carrier issues it.
Condo insurance cost questions
What affects the cost of condo insurance?
Your own choices (Coverage A, the contents limit, liability and your deductibles) plus things you do not control: the master policy type, the building, where it is and how the unit is used. A quote on your own limits shows how each one plays out for you.
How much is condo insurance?
Across all states, NAIC's latest homeowners report puts the average HO-6 premium at $658 a year, based on 2023 data18. State averages run from $331 in Wisconsin19 to $1,146 in Florida20. Your own price depends on what the master policy leaves you, your limits and deductibles, the building and how you use the unit.
How can I lower my condo insurance premium without cutting coverage I need?
Size Coverage A to what the master policy actually leaves you, pick a deductible you could pay in dollars, and ask each company which discounts or credits apply to your unit. Then compare several companies on the same limits, since one company's quote shows only one company's answer.
What sets the cost of co-op insurance?
Mostly what the co-op corporation's building policy leaves to you, what you own inside the apartment and the limits you choose for belongings and liability. Get the building policy summary from the managing agent first, then quote your own limits.
Why can't I compare a condo quote with a quote on a house?
A condo policy insures only your share of the building, so it is a different product from a whole-house policy. Comparing the two tells you nothing about whether either one is right. Compare quotes for the same condo coverage instead.
Does a higher deductible lower my premium?
A higher deductible means you keep more of a loss yourself. How much, if anything, it changes the premium differs by carrier, so ask to see the quote at more than one deductible and pick one you could pay tomorrow.
Is a hurricane deductible a percentage of the building's value?
Do not assume so. Your own policy's form and declarations page say what the percentage applies to. Virginia's rule for owner-occupied units, for example, measures its deductible cap against the unit's own dwelling limit rather than the building value13, while Florida's statute speaks of "policy dwelling limits" without defining the phrase for unit-owner policies11. Check the base and the dollar figure on your declarations page.
Does the master policy affect what I pay?
Yes. Its type decides how much Coverage A you need to buy, and its deductible decides how much of a building loss can come back to you through an assessment. Read the master policy summary before you set either limit.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.