Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Pennsylvania condo unit owners
Pennsylvania Condo Insurance
The licensed agent who works through this site shops unit-owner coverage with several companies, and the Pennsylvania answer is short: the association's required policy covers your unit but not the improvements and betterments installed in it1, and the board levies its uninsured deductible back on owners2.
Your HO-6 is where the upgrades, your belongings and your liability get insured, and its loss assessment coverage may help with your share of that deductible; check your policy.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
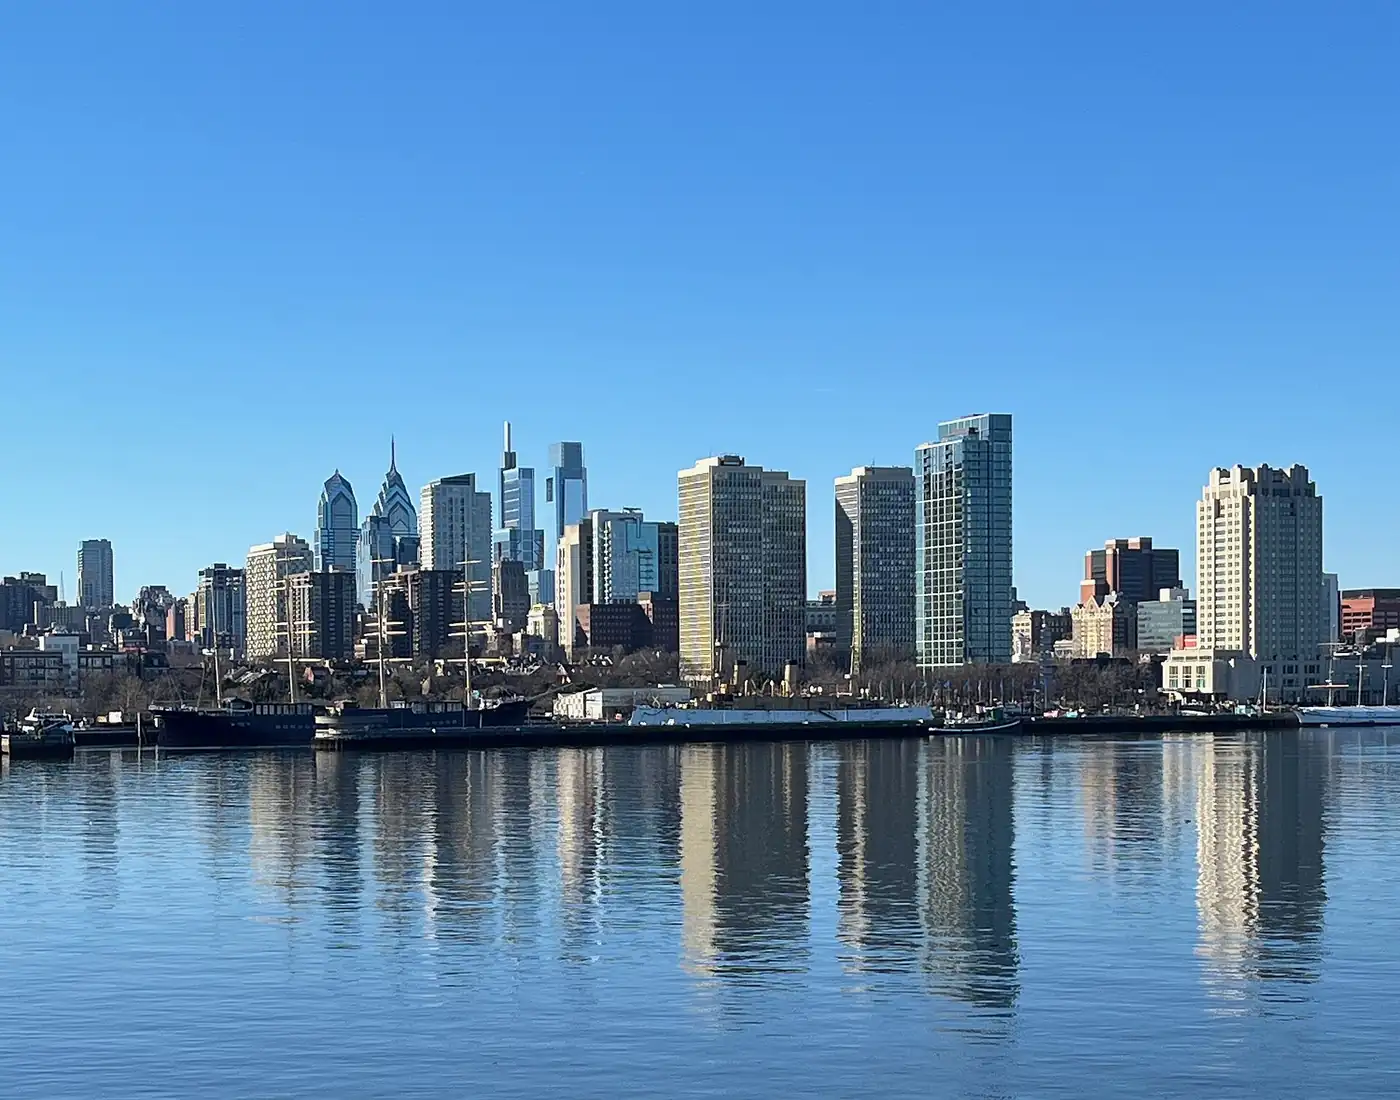
Center City Philadelphia skyline and Delaware River waterfront towers seen from the Camden waterfront. Photo: Bronzeage10, CC BY 4.0, via Wikimedia Commons.
Pennsylvania Condo Insurance: your upgrades sit outside the master policy
Under the Uniform Condominium Act, the association insures more of your unit than many owners expect, minus the upgrades.
- The unit itself is on the master policy
- Improvements and betterments are yours
- Older buildings may play by other rules
The property policy the association must carry reaches the units themselves, but not the improvements and betterments put into them1 (68 Pa.C.S. § 3312(a)(1)1).
What that leaves you: the upgrades, your belongings and your personal liability. The middle option below, "All-in, minus upgrades", is close to that rule, as a general picture; your declaration and the master policy decide.
Go deeper: builder finishes, upgrades and buildings created before the Act
Which items count as improvements and betterments is the practical question. Whether the original builder's cabinets, floors and fixtures sit on the master policy or on yours is settled by your declaration and the policy wording, so ask the board for the master policy or its certificate before you choose limits.
Older Pennsylvania condominiums may follow different rules
The Act covers condominiums created after its 1980 effective date, and its insurance section is not one of the parts extended to condominiums created earlier3 (68 Pa.C.S. § 31023).
If your building is older, do not assume the master policy follows the rule above. Your declaration, bylaws and the master policy itself are the rules that count, so read them before you set your Coverage A limit.
Plan for your share of the master deductible now
Under Pennsylvania's Act, the board levies the uninsured deductible. What matters is how it is allocated, and whether any lands on you.
- The executive board levies the deductible
- Ask how past losses were allocated
- Your own HO-6 has separate deductibles
When a loss falls inside the master policy deductible, or the association self-insures it, the executive board levies that amount under the Act's rules for allocating expenses2 (68 Pa.C.S. § 3312(i)2).
Ask the board how it has split deductibles before, and whether the declaration adds anything.
Go deeper: your own deductibles and the lender cap
Your HO-6 has its own deductible, and some policies carry a separate wind or hail deductible. Read every deductible on your declarations page.
A loan sold to Fannie Mae adds a ceiling: no higher than the greater of 5% of the unit policy's coverage amount or $2,500, across the required perils4.
The resale certificate shows the reserves in writing
Buying a unit? One document shows the planned projects and the reserves set aside for them.
- Planned capital spending, three fiscal years
- Reserve balance for capital work
- Earmarked money for specific projects
On resale, the certificate has to show planned capital spending for this fiscal year and the next two, plus the reserves held for capital work and any amount earmarked for a particular project5 (68 Pa.C.S. § 3407(a)(4), (5)5).
Big plans plus a thin reserve can point to a special assessment.
Go deeper: if you already own the unit
You will not see a resale certificate unless you sell, so ask the board for the same figures. Your declaration and bylaws show how reserves are planned and funded in your building.
No HO-6 from the Pennsylvania FAIR Plan: keep comparing
The state's residual market offers no condo unit form, which makes a wide comparison more useful, not less.
- No homeowners unit owners form listed
- Dwelling and commercial forms only
- Declined? Ask more companies
The Pennsylvania FAIR Plan offers no homeowners (HO 00 06) form; it lists only the dwelling forms DP-0001 and DP-0002 for 1-4 family dwellings and the commercial Standard Property Policy CP-00996.
If one company declines your unit, the next step is another company, not the plan.
Go deeper: could a condo unit go on a dwelling form?
The plan's listing does not answer whether a condo unit could be placed on one of its dwelling forms. Treat it as a question to ask, not a plan to count on, and keep comparing voluntary companies.
Claim stalled? Pennsylvania's Insurance Department takes the call
If your insurer will not fix a claim, a nonrenewal or a policy term, the state consumer line is next.
- A toll-free consumer hotline
- Call after your insurer says no
- Keep your paperwork within reach
Pennsylvania Insurance Department consumer line: 1-877-881-63887.
Have your policy number, the claim number and the insurer's letters ready before you dial.
Five Pennsylvania gaps to close before a claim
Each ties back to how Pennsylvania splits a loss. Most come down to one limit or one question.
- Upgrades and the deductible levy first
- No residual HO-6 to fall back on
- One question per gap
Go deeper: the detail behind each Pennsylvania gap
Water. Because the association's required policy covers the units, a leak from upstairs can start as the association's claim. In an older building outside the Act's insurance section, the declaration decides. Read water damage from the unit above for the claim sequence.
Coverage letters. Coverage A insures what is permanently installed in the unit, where the association's policy does not already reach8. Coverage C pays for furniture, clothes, electronics and other personal items after a theft, or when a covered loss damages or destroys them9. Built-in appliances generally belong to Coverage A under the common HO-6 form many carriers use10; check your policy.
Coverage D covers the added cost of living elsewhere if covered damage leaves the unit unlivable11, and Coverage F covers medical bills for people injured at your place12. Use the condo contents calculator to sort A from C, and see how much condo insurance you need.
Deductible. With a Fannie Mae loan and a per-unit master deductible, your policy limit cannot be less than that per-unit deductible13. Ask whether your loss assessment coverage pays a deductible assessment; see loss assessment coverage.
Vacancy. Read your HO-6 for heat, occupancy and vacancy conditions and say how the unit is used. Check your policy.
Assessments. For the levied deductible, loss assessment coverage may help pay your share when the community suffers a loss, as long as your own policy covers the cause14. An assessment for a roof that simply wore out is maintenance, and loss assessment coverage is generally not built for it.
Line up several companies on your betterments
Under the Act, your upgrades sit outside the master policy, so your HO-6 insures them. See how several companies treat that list.
- Same betterments, same limits, side by side
- Ask which discounts apply, if any
- The decision stays with you
A single-company agent can place you with that one company. A side-by-side of several shows whether another treats your improvements, deductible choice or loss assessment limit differently.
If nobody has asked what you have upgraded since you moved in, your Coverage A may still reflect the day you bought.
Discounts and credits: ask each company, because availability varies by company and state. Any that apply show on the quote.
Go deeper: how the Pennsylvania comparison runs
The agent checks HO-6 options with several companies and matches each one to the improvements and betterments your master policy leaves out. You compare the forms and deductibles, and the decision is yours.
Nothing is bound by a quote; coverage starts when a policy is issued in your name. Pennsylvania condo owners can request quotes here; the agent disclosure explains licensing.
Bring this short list and skip the back-and-forth
Five items let the comparison start from your building's real rules, and none of them is hard to find.
- The creation year matters here
- Note who installed each upgrade
- Partial is fine to start
- The declarations page of any HO-6 you carry now.
- A certificate or summary of the association's master policy.
- The insurance section of your declaration or bylaws, and the year the condominium was created.
- Your improvements and betterments: floors, cabinets, counters, built-ins.
- How you use the unit: home, rental or part of the year.
Then send a quote request. Background: HO-6 vs HO-3 and the condo insurance cost factors.
Pennsylvania condo owner questions
Is condo insurance required in Pennsylvania?
A requirement often comes from your mortgage. Under Fannie Mae's guide, a borrower needs a unit owners policy if any of the interior or improvements falls outside the master policy, or if that policy has a per-unit deductible15. Under the Act, improvements and betterments are outside the association's required coverage1. Your declaration or bylaws may also require a policy.
Which Pennsylvania laws shape condo owners' insurance?
For condominiums created after the Act took effect, its insurance section sets the association's property coverage, leaves out improvements and betterments, and has the board levy the deductible. For older condominiums, that insurance section is not one of the parts extended to them3. On resale, the certificate must disclose reserves and planned capital spending5.
Does the association's policy cover the inside of my Pennsylvania unit?
In a condominium under the Act, the required policy covers the unit but not the improvements and betterments installed in it1. Your declaration and the master policy wording decide which finishes are yours. In an older building, read the declaration first, because the Act's insurance section may not apply.
Can I get an HO-6 from the Pennsylvania FAIR Plan?
No. The plan offers no homeowners form; it lists dwelling forms for 1-4 family dwellings and a commercial form6. If you are declined, keep comparing voluntary companies, and ask each one what it would need to see to write the unit.
Who pays the master policy deductible in Pennsylvania?
The executive board levies the uninsured deductible portion of a loss as an assessment2. Ask how your board allocates it, whether to every owner or to the units involved, and whether your HO-6 loss assessment coverage would pay your share.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.