Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Virginia condo unit owners
Virginia Condo Insurance
A licensed insurance agent who works through this site compares condo coverage across several companies for Virginia unit owners. The quick answer: a state regulation sets a minimum dwelling limit on your unit policy1 and, for an owner-occupied unit, caps property deductibles, wind and hail included2.
Everything else turns on your condominium instruments, which decide what the master policy covers.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
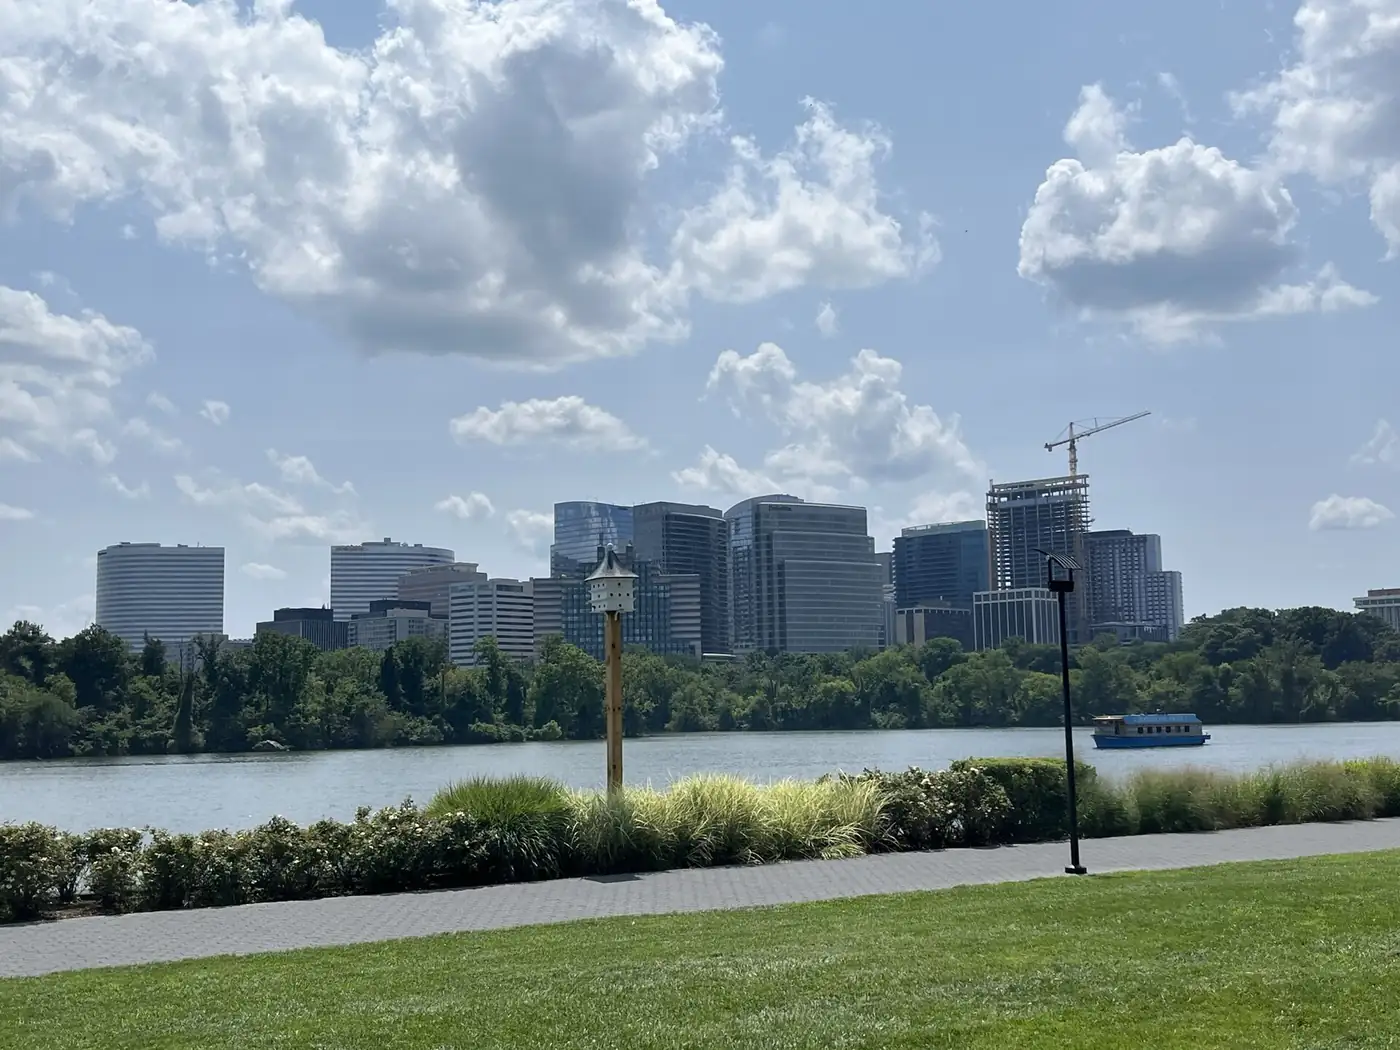
Rosslyn (Arlington) tower skyline across the Potomac River from Georgetown Waterfront Park. Photo: Cornflower123, CC0, via Wikimedia Commons.
Virginia Condo Insurance: your documents set the master policy
The statute leaves the master policy to your condominium instruments. Read them and you know what your HO-6 must fill.
- Start with the declaration and bylaws
- Less on the association means more on you
- Your resale certificate maps the gaps
Va. Code § 55.1-1963(A)3 does not itself require a master property policy; it lets the condominium instruments require the association to carry one3.
If your instruments ask the association for less, more of a loss lands on your own unit-owner policy.
Go deeper: the instruments and your resale certificate
What the instruments can ask the association to insure
The instruments may call for a master casualty policy with fire and extended coverage at full replacement value of the structures, a master liability policy covering the association, board, managing agent and all unit owners, and any other policies they name3.
The resale certificate names your deductible risk
When a unit is sold, the resale certificate has to describe the insurance the association carries for owners, list any coverage owners are told or advised to buy, and warn that the governing documents can put all or part of a claim's deductible on an owner4 (Va. Code § 55.1-2310(A)(14)4).
Keep your copy. It is the quickest map of what your own policy has to cover.
A floor under your limit, a cap on your deductible
A state regulation sets the least dwelling coverage a unit policy can carry and limits how large any property deductible can get.
- Minimum limit for dwelling and fixtures
- Deductible cap measured on your unit, not the building
- Applies to owner-occupied units
Minimum dwelling coverage for a condo unit
Under 14VAC5-342-40(A)(2)1, a condo unit policy has to carry a limit of at least $5,000 for the dwelling and fixtures the owner is responsible for1.
Wind and hail deductible cap
Only one deductible applies per loss, and no property deductible can be set above 10% of the policy's own dwelling limit2 (14VAC5-342-70(H)2).
Which unit owners the cap reaches
The cap is tied to owner-occupied units, and it does not reach lender-placed or VPIA policies2.
The minimum is a floor. Your limit should match what you own.
Go deeper: sizing your limit and reading storm wording
Insurers may use a special deductible for wind, hail or theft2. On a unit policy, the cap is measured on your unit's dwelling limit, not the value of the building2.
Set your limit from what it would cost to rebuild the finishes and upgrades you own; how much condo insurance to carry walks through it.
Your policy form says when a hurricane or named storm deductible starts to apply. Read that wording and your declarations page before storm season.
A reserve study shows your assessment risk in advance
The board's reserve study gives you a read on special assessment risk before you pick a loss assessment limit.
- Ask for the latest reserve study
- Compare recommended and actual reserves
- Ask about structural inspections too
Unless the condominium instruments say otherwise, the executive board has to run a reserve study at least every five years, look at it again at least once a year, and adjust the budget and assessments as it judges necessary5 (Va. Code § 55.1-1965(B)-(C)5).
A wide gap between recommended and actual reserves is worth knowing about before you set your limit.
Go deeper: what the budget has to show
When the study shows a need, the budget must show the replacement cost and remaining life of capital components, current reserves, planned contributions, and recommended versus actual reserves5.
Ask the board, too, whether the building has had a recent structural or engineering inspection and what it found.
Turned down? VPIA also writes condo unit owners
If private companies say no, the state's residual market plan writes unit owners, just not on a form titled HO-6.
- Dwelling fire forms with unit-owner endorsements
- A loss assessment endorsement is listed
- The regulation's deductible cap does not reach it
VPIA writes condo unit owners on dwelling fire forms, not a form titled HO-6, with unit-owner additions endorsements (FL-32 broad and FP FL-31 basic) and an FL-50 residential association loss assessment endorsement6.
A dwelling fire package can differ from an HO-6 in what it covers. Compare it line by line with any private offer.
Go deeper: how VPIA reaches your fixtures
When a dwelling fire form is issued to a unit owner for contents, 10% of the contents limit extends to the owner's fixtures, additions and alterations6. Remember that the deductible cap above does not apply to VPIA policies.
Claim going nowhere? The Bureau of Insurance takes complaints
If a claim stalls or a renewal surprises you, the state's Bureau of Insurance lists a toll-free number for complaints.
- Toll-free line on the complaint page
- Have your policy number ready
- Keep insurer letters close by
The Bureau of Insurance lists 1-877-310-65607 on its complaint page.
Gather your policy number, claim number and any letters from the insurer before you call.
Five gaps that decide what a Virginia claim pays
Check each gap against your documents before a claim, while a fix is still simple.
- Your instruments shape every leak claim
- The deductible may be passed to you
- Renting the unit can change your protections
Water from the unit above: whose policy responds
How a leak splits depends on what your instruments make the association insure. Your HO-6 takes what the master policy leaves.
Coverage A or Coverage C for your unit
Coverage A insures what is built into the unit and not already on the association's policy8. Coverage C pays when what you keep inside is damaged, stolen or destroyed by a covered loss9.
The master policy deductible
Your resale certificate warns the documents may put some or all of a deductible on you. Ask for the current figure yearly.
Vacant, rented or seasonal condo units
The deductible cap is tied to owner-occupied units. Rent the unit or leave it empty, and the form can change.
Special assessments and loss assessment coverage
It helps with your share of certain association bills. Underfunded reserves, with no covered cause behind them, usually fall outside it.
Go deeper: the details behind each gap
When a leak makes the condo unlivable
Should covered damage make the unit uninhabitable, Coverage D pays what it costs you, beyond your usual expenses, to live somewhere else while it is fixed10. Since the governing documents may put all or part of the deductible on you, a leak can cost you that deductible even when the master policy pays. More: water damage from the unit above.
Built-ins, belongings and your coverage
Coverage C reaches furniture, clothing, computers and TVs9. Built-in appliances usually fall under Coverage A on the standard HO-6 form; check your policy11. Use the contents calculator or compare the condo form with a house form.
Lender rules on the master policy deductible
Read the governing documents for the amount and when it is charged. When your loan follows Fannie Mae's guide and the master policy carries a per-unit deductible, your own policy has to be at least as large as that deductible, or as the cost of restoring the uncovered interior if that is more12.
Rented condo units and the application
If you rent the unit or leave it empty, tell the agent: the form, and which protections apply, can change. The application should describe the use plainly.
When loss assessment coverage pays
If your own policy covers the cause, loss assessment coverage may help with your share when the association assesses owners for a community loss, for example wind damage to several roofs beyond the master policy limits13. An assessment that does not trace to a covered cause usually falls outside it, which is why the reserve study matters. See loss assessment coverage.
Put your renewal next to a few others before you sign
Another company may read your unit, your deductible and your use differently. You only see that when quotes sit side by side.
- Same limits across every company
- Ask what discounts and credits apply
- Have your minimums and caps checked
An agent tied to a single company can show you that company's policy, and nothing to measure it against. Comparing several on identical limits closes that gap.
Plenty of owners have never had their walls-in amount or loss assessment limit looked at since closing. Ask every company which discounts or credits your unit qualifies for; availability varies, and a quote shows what applies.
Line up Virginia quotes on your exact limits
Hand over your certificate and master policy summary. The agent does the comparing, and you pick.
- Options from several companies
- A quote does not bind coverage
- Your current policy stays until a new one is issued
The agent compares unit-owner options against your instruments, your resale certificate and the association's master policy. You review the choices and pick one.
What to have ready:
- Your present declarations page, if you are insured today.
- The master policy certificate or summary the association provides.
- Your resale certificate, or the declaration's insurance section.
- Improvements you or an earlier owner made.
- Whether the unit is your home, a rental or a part-year place.
Virginia condo owners can request quotes through this site; the agent's license details are in the agent disclosure.
Go deeper: what moves an HO-6 quote
See the factors that move an HO-6 quote, or send a quote request when you are ready.
Questions from condo owners in Virginia
Is condo insurance mandatory in Virginia?
The requirement usually comes from your lender or your condominium documents. A lender that follows Fannie Mae's guide will want a unit owners policy if the master policy does not cover part of the interior or improvements, or if it has a per-unit deductible14. Your resale certificate lists any coverage owners are required or recommended to carry4.
What is the minimum dwelling coverage on a Virginia HO-6?
At least $5,000 of coverage for the dwelling and fixtures you, as the unit owner, are responsible for1. Treat it as a floor. Price the finishes and upgrades you own, and set your limit from that number instead.
Can my wind deductible in Virginia be based on the whole building's value?
Not on an owner-occupied unit policy the rule reaches: a property deductible can be no more than 10% of the policy's own dwelling limit2, meaning your unit's limit, not the building's value. Check your declarations page to see how your own deductible is set.
Do I have to pay my association's master policy deductible?
It depends on your governing documents. Virginia requires the resale certificate to warn that they may make you responsible for all or part of a deductible4. Read the insurance and assessment sections, and ask the association.
Does VPIA write HO-6 policies for condo owners in Virginia?
No form titled HO-6 is listed. VPIA covers unit owners on dwelling fire forms with unit-owner endorsements6. Because those forms can differ from an HO-6, compare the coverage line by line before you accept one.
How often must a Virginia condo association do a reserve study?
At least once every five years, with a review at least annually, unless the instruments say otherwise5. Ask the board for the latest study before you choose a loss assessment limit.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.