Your one stop for condo insurance.
Stop calling agent after agent for one quote each. One call, and a licensed agent shops your HO-6 with several insurance companies, A-rated options included, then lays the offers side by side. You pick.
You are in the right place. Keep reading for the answer, or call and let the shopping start now.
Tampa condo unit owners
Condo Insurance Tampa
The licensed agent behind this site compares HO-6 policies from several companies for Tampa condo owners, and the Hillsborough County storm log points to the first decision worth getting right: the hurricane deductible you would actually owe after a claim.
Next come the Florida rules on what the association insures, what falls to you, and how damage to the building can turn into an assessment on your unit.
- One call, not ten
- Several companies shopped for you
- No obligation: a quote never binds
Compare my condo quotes
Several companies, side by side. You decide.
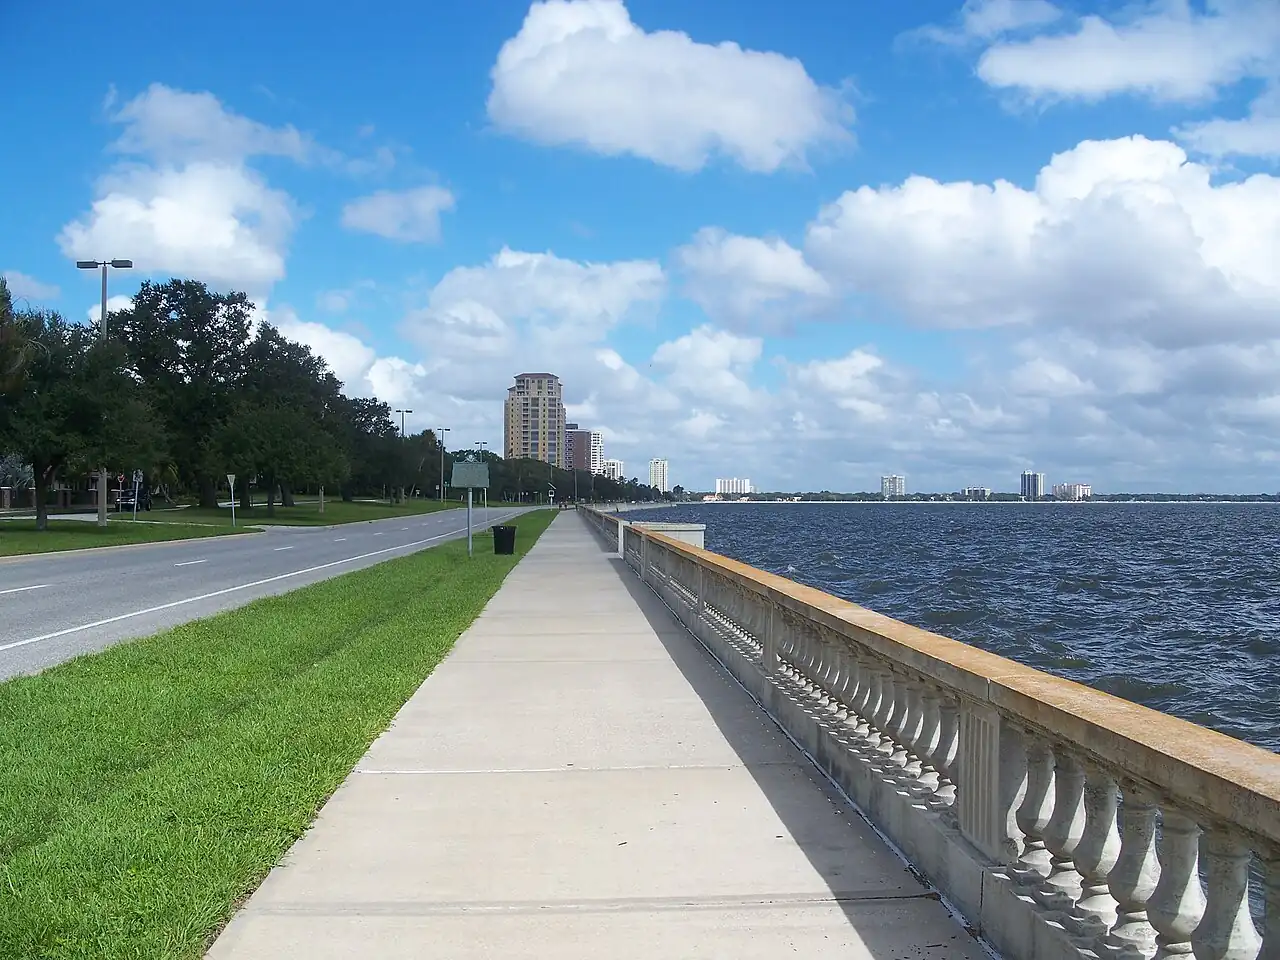
High-rise buildings along the Bayshore Boulevard seawall on Hillsborough Bay, Tampa, Hillsborough County. Photo: Ebyabe, CC BY 2.5, via Wikimedia Commons.
Read Hillsborough County's storm record the right way
The federal storm log shows how often wind events were reported for the county. Use it to decide which deductible to study first.
- Each count is a report, not a separate storm
- Zone reports repeat when one storm crosses zones
- Wind is what a hurricane deductible is about
Hurricane and Tropical Storm rows are filed per forecast zone, so a storm that crosses more than one Hillsborough County zone is listed more than once. Thunderstorm Wind and Tornado rows are filed for the county itself.
For a unit owner, a hurricane claim meets two deductibles. One sits on your HO-6. The other sits on the association's master policy, and whatever the association pays toward it comes out of owners' pockets, sometimes as a special assessment.
Go deeper: what the storm log can and cannot tell a Tampa owner
The database records events that were reported. It does not measure damage to any condo building, and it says nothing about coming seasons.
The same search also lists 1 High Wind report6 and 2 Strong Wind reports7 for the county's zones.
Not every wind loss is a hurricane loss. Whether your hurricane deductible or your regular deductible applies to a thunderstorm or tornado claim depends on how your policy defines a hurricane. Check your policy, and ask the company to point to the wording.
Turn your Tampa hurricane deductible into dollars
A percentage deductible is easy to misjudge until you multiply it out. Run the numbers on your own limits before you renew.
- Florida names the options insurers must offer
- Percentage options climb as your limits climb
- Your declarations page shows the real figure
Florida makes an insurer offer, before it issues a personal lines residential policy, a $500 hurricane deductible along with choices of 2 percent, 5 percent and 10 percent of the policy dwelling limits8, with exceptions (Fla. Stat. § 627.701(3)(a)8).
The open question on a condo policy is the base. The statute says policy dwelling limits and leaves that phrase undefined for condominium unit owner policies9. Enter Coverage A alone, then Coverage A and C together, and compare the two answers.
Florida hurricane deductible math for a condo unit (HO-6)
This applies the options in Florida's hurricane deductible statute for personal lines residential policies. Ask your insurer whether it applies them to your HO-6. Enter your own limits. The tool multiplies; it does not quote or price anything.
Why the choice: the statute states its percentages as a share of "policy dwelling limits" and does not define that phrase for a unit-owner policy9. Your insurer's form decides. Check your declarations page.
| Option in the statute8 | Your hurricane deductible |
|---|
These are the options the statute tells insurers to offer, subject to its exceptions. They are not a complete list of what an insurer may write: the statute carries exceptions this tool does not model, and an insurer does not have to offer a percentage option that works out below the flat option. Your declarations page shows the deductible that applies to you.
The tool only multiplies what you type by the statute's options. It is not a quote and says nothing about what a company will offer you.
Go deeper: the master policy deductible, and a lender's ceiling on yours
Your building's master policy has its own hurricane deductible, set for the whole association. When a storm loss falls inside it, the board pays from association funds or levies a special assessment on owners, split the way your declaration says.
Florida requires every unit owner policy to carry no less than $2,000 of loss assessment coverage for all assessments arising from one direct loss, when the loss is a type the policy covers10 (Fla. Stat. § 627.714(1)10). Whether that coverage pays toward an assessment for the association's deductible depends on your form, so ask before you count on it. The loss assessment coverage guide shows how to size a limit.
If your loan follows Fannie Mae's guide, your own deductible has a cap: the greater of $2,500 or 5% of the unit policy coverage amount, for all required perils11. Hold any percentage choice up against it.
Tampa condo buildings run from towers to small walk-ups
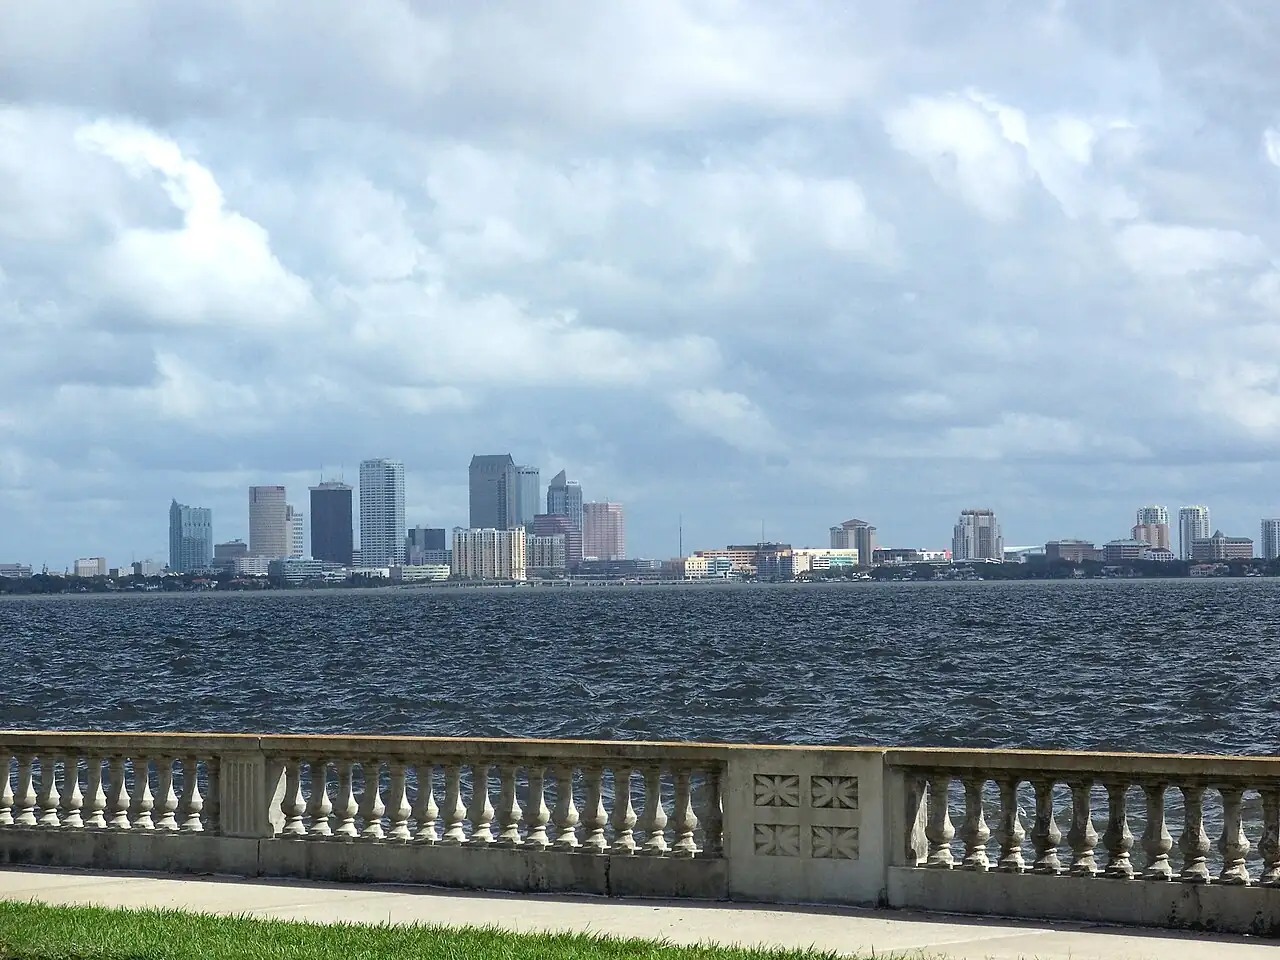
The size of your building decides how much the master policy handles and how much your HO-6 has to carry.
- Large buildings run on a master policy
- Your declaration draws the dividing line
- Smaller buildings still split coverage the same way
Inside city limits, 21.4 percent of housing units sit in structures with 20 or more units, per the Census Bureau's ACS 2020-2024 5-year estimates12.
Another 6.7 percent of the city's units are in structures with 10 to 19 units13.
Countywide, the share of Hillsborough County housing units in structures with 20 or more units is 11.0 percent14.
Whatever the building's height, a condominium runs on a master policy for the structure and a declaration that says where that policy stops. Past that line, your HO-6 takes over.
Go deeper: the unit counts behind the percentages
The Census estimate puts 38,948 Tampa housing units in structures with 20 or more units15, out of an estimated 182,425 housing units in the city16.
These counts cover every kind of housing unit, rentals included, not only condominiums. They describe the city's buildings, not yours. Your deed, declaration and the association's papers tell you what your building is.
Older Tampa buildings: ask about reserves before an assessment finds you
Age shapes what a building needs next. Reserves and repair plans decide whether those costs arrive through dues or a special assessment.
- Median year built comes from Census data
- SIRS reserves cannot be voted away
- Upkeep is not an insured loss
The median year built for Tampa housing is 1985, per ACS 2020-2024 5-year estimates17.
For Hillsborough County as a whole, the median year built is 199118.
Florida bars owners in an association that needs a structural integrity reserve study (SIRS) from voting to skip or shrink reserves for the study's items, for budgets adopted on or after Dec 31, 2024, and that money cannot be diverted to other costs19 (Fla. Stat. § 718.112(2)(f)2.b., 3.19).
If reserves run short, owners close the gap through higher dues or a special assessment. That is maintenance, not a covered loss, so an HO-6 generally will not pay it.
Go deeper: where loss assessment coverage fits, and what to ask the board
Loss assessment coverage answers a different bill. It responds when the association assesses owners after a direct loss of a kind your policy covers, such as wind damage to the building. Florida's floor is $2,00010; your building's master deductible and your ownership share tell you whether that floor is enough.
- Ask whether the association must have a SIRS, and request the most recent study.
- Ask for the current budget and whether any special assessment is planned or pending.
- Ask for the master policy certificate, including its hurricane deductible.
Whether a given building must have a SIRS depends on the building, so let the association's answer, not the city's median, settle it.
What Florida's condo act leaves on your side of the line
State law lists the interior items the master policy must leave out. For a Tampa owner, that list is the heart of Coverage A.
- Coverings, fixtures, appliances, cabinets, counters
- Replacements and upgrades are on the list
- Everything you own inside is yours
The association's coverage has to exclude everything you own in the unit and, where they serve your unit alone, the floor, wall and ceiling coverings, electrical fixtures, appliances, water heaters and water filters, built-in cabinets and countertops and window treatments, including their replacements20 (Fla. Stat. § 718.111(11)(f)3.20).
The statute then assigns every one of those items, along with any policy covering them, to you as the unit owner21 (Fla. Stat. § 718.111(11)(f)3., (g)21).
Pick a building type below to see the split drawn out. The Florida condo insurance guide walks through each rule in full.
Go deeper: turning the list into a Coverage A figure
Coverage A picks up permanently installed property in the unit that the association's policy does not already insure22. Price each listed item at what it would cost to replace today, then add upgrades, including ones a prior owner made.
Equipment that serves several units is not on your list. Ask the manager how shared water heaters or fixtures are treated.
Need a number to start from? Try the condo coverage amount guide. Wondering what an endorsement adds to a Tampa policy? Read about the HO-6 form and its add-ons.
Citizens: Florida's fallback when a Tampa unit is hard to place
If companies decline your unit, Florida's residual market may write it. Check occupancy and value first.
- Written for owners who live in the unit
- The unit's value has a ceiling
- County status can raise that ceiling
Citizens offers condominium unit owner coverage, both an HO-6 and a wind-only HW-6, to owners who live in the unit; it reaches certain interior features, personal property, additional living expenses and liability, but not the outside of the building23.
Value is the second test. Citizens turns away a single unit when replacing the unit and its contents would cost $700,000 or more; where the Office of Insurance Regulation has found a county short of reasonable competition, the cutoff moves up to $1 million24 (Fla. Stat. § 627.351(6)(a)3.24).
The county finding on record is OIR's order in Case No. 165625-14, dated December 22, 2014: it found no reasonable degree of competition only in Miami-Dade and Monroe Counties and made no determination for Hillsborough or any other county25.
Ask Citizens which value limit it applies to your Tampa unit today.
Go deeper: renters, seasonal owners and the wind-only option
Test the value rule with Coverage A and Coverage C added together, since it looks at dwelling and contents as one figure.
Owner occupancy is part of how the residual market frames its condo policy. A Tampa unit leased to tenants, or used as a winter place, needs a straight answer from Citizens on eligibility before that fallback goes into your plans.
The HW-6 covers wind only, so it is paired with other coverage for the rest of your risks.
Check your Tampa building's records before you set limits
Public records and association papers confirm when your building went up and how its insurance is arranged.
- Year built from the parcel record
- Association filings with the state
- Master policy summary from the manager
Year built: look up the building in the property search26 run by the Hillsborough County Property Appraiser27. The parcel details tell you which reserve and repair questions to raise.
State condo records: DBPR's County Summary Report, in its file updated 09/26/2026, lists 570 condominium projects in Hillsborough County28.
Those projects hold 38,906 units; DBPR notes the report covers only approved and recorded projects with 8 or more units, so smaller condominiums are left out29.
The DBPR condominium public records page30 offers the condominiums-by-county download if you want to find your association by name.
Go deeper: the association papers that matter as much as public records
From the manager, ask for the declaration's insurance section, the master policy certificate with its deductibles, and the latest budget. The declarations page guide shows where each figure sits on your own policy.
Buying? The checklist for realtors and lenders covers what a lender will want to see before closing.
Compare Tampa HO-6 quotes on identical limits
A single company's quote shows how that company sees your unit. Several, lined up on the same terms, show where they part ways.
- Same Coverage A, C and hurricane deductible
- Ask each company about discounts
- Nothing binds until a policy is issued
Tampa condo owners can ask for quotes through this site, and the agent who compares them holds a Florida insurance license.
Every option is quoted on the limits you pick, so differences show up in terms, deductible choices and exclusions instead of in a shifted coverage amount. Ask each company which discounts or credits it applies to your unit; the quote lists any it gives.
A quote is information only. It binds nothing, and coverage begins only once a policy is issued.
Go deeper: how a Tampa comparison runs, step by step
- Share what you have: where the unit is and its size, last year's declarations page, and whatever the manager gave you about the building's coverage.
- The agent sorts out which interior items fall to you under Florida's list and reads your hurricane deductible and loss assessment limit as they stand.
- Quotes come back from multiple carriers, each priced on the Coverage A, Coverage C and deductible figures you settled on.
- A side-by-side sheet flags where terms, exclusions or applied credits differ between them.
- Take one, or keep the policy you have. The choice stays yours.
More Florida condo insurance reading for Tampa owners
The statewide guide and the other city pages fill in what this page leaves out.
- Every Florida rule in one place
- County numbers for other cities
- Guides on HO-6 parts and loss assessment
Start with the Florida condo insurance page for the full set of state rules.
Other Florida city pages: Miami, Fort Lauderdale, St. Petersburg, Orlando.
For the coverage parts themselves, read the HO-6 insurance guide, and build an inventory with the condo contents calculator.
Tampa condo insurance questions
What does HO-6 coverage include for a Tampa condo owner?
An HO-6 insures your side of the split. Coverage A handles the interior items Florida's condo act keeps off the master policy, such as coverings, fixtures, appliances, cabinets and countertops. Coverage C handles your belongings. Most forms add extra living costs after a covered loss and personal liability. Limits and exclusions vary by form, so read yours.
Is there a rule of thumb for how much condo insurance a Tampa unit needs?
No single formula fits every unit. A workable start: set Coverage A to replace the items Florida's list leaves to you plus any upgrades, set Coverage C from a room-by-room inventory, and weigh loss assessment above the state's $2,000 minimum10 against your master policy's deductible. The contents calculator helps with the inventory.
How do I figure a percentage hurricane deductible on my Tampa HO-6?
Multiply the percentage by the base your insurer uses. Florida's statute ties the percentage options to policy dwelling limits and does not define that phrase for unit owner policies Fla. Stat. § 627.701(3)(a)9, so ask whether your company uses Coverage A alone or A plus C. The tool on this page runs both; your declarations page shows the dollar figure that applies.
Can hurricane damage to my Tampa building become a bill for me?
It can. If a storm loss lands inside the master policy's deductible or runs past its limits, the association may cover the gap with a special assessment on owners. Loss assessment coverage on your HO-6 may help when your policy covers the cause; whether it pays toward the association's deductible depends on your form, so ask.
Does Citizens write condo coverage for Tampa unit owners?
For owners who live in the unit, Florida's residual market lists an HO-6 and a wind-only HW-6 23. A unit is not eligible when its dwelling and contents replacement cost together reach $700,00024, unless the state has found the county short on competition. OIR's order in Case No. 165625-14 (December 22, 2014) named only Miami-Dade and Monroe and made no determination for Hillsborough25.
My Tampa townhouse association insures the shared roof. Do I need an HO-6 or an HO-3?
The building's look does not decide it; the legal form of ownership does. If your community was created as a condominium, Florida's condo act split applies and an HO-6 usually fits. If you own the structure and the land under it, an HO-3 may be the right form. Read your deed and declaration, then see HO-6 vs HO-3.
The Tampa condo I am buying has a special assessment attached to the sale. What should I find out?
Ask the association what the assessment pays for. A repair after a covered loss, such as storm damage, is a different matter from reserve funding or planned upkeep, which an HO-6 generally does not pay. Read your contract for who pays it at closing, and ask each company quoting you how its form treats an assessment levied before the policy began.
The association has an open claim on its master policy while I am under contract on a Tampa unit. How does that affect me?
Ask the manager in writing what the claim covers, where it stands, and whether an assessment could follow if the claim is reduced or falls inside the master deductible. Ask your lender how it views the claim too. Then set your loss assessment limit with that answer in mind, and tell each company quoting your HO-6 about the open claim.
Before you renew, make one call.
A licensed agent compares several companies on the same limits. Asking changes nothing on your policy, and a quote never binds you.